Australia is facing the largest intergenerational wealth transfer in its history, with an estimated $5.4 trillion expected to pass from older Australians to younger generations. Now, renewed warnings about the possible return of inheritance tax are raising an important question: is it time to rethink how we pass on family wealth?
For millions of older Australians, the family home represents their greatest financial asset.
After decades of mortgage repayments and rising property values, many retirees have accumulated substantial wealth in their homes. Yet that wealth often remains untouched until the property is eventually sold or passed on to the next generation.
But with renewed debate about inheritance taxes, rising living costs and younger generations struggling to enter the property market, traditional approaches to inheritance may be changing.
One option worth understanding is a reverse mortgage, which can allow eligible older homeowners to access part of their property wealth without having to sell their home.
Could this offer families a more flexible way to manage their wealth across generations?
Why Is Australia Talking About Inheritance Tax Again?
A recent Yahoo Finance Australia report has reignited debate about whether Australia could eventually reintroduce inheritance taxes, sometimes called death duties.
The report quotes estate planning lawyer Morgan Solomon, who believes the return of some form of inheritance tax may eventually become inevitable.
His reasoning is straightforward: as trillions of dollars in wealth pass between generations, governments may increasingly consider taxing inherited wealth.
Australia previously had inheritance and estate taxes, but these were progressively abolished, with the final state duties disappearing in the early 1980s.
Importantly, Australia does not currently have a general inheritance tax, and the Federal Government has stated that it has no plans to introduce one.
The suggestions that a future tax might apply to estates worth $5 million or $10 million are speculative. No such thresholds have been legislated or formally proposed by the government.
Nevertheless, the discussion highlights an important issue for older homeowners: how should you manage the wealth you’ve accumulated, both for yourself and for future generations?
The $5.4 Trillion Wealth Transfer: Why the Family Home Matters
Australia is entering an unprecedented period of wealth transfer.
An estimated $5.4 trillion is expected to move between generations over the coming decades, much of it from Baby Boomers to their children and grandchildren.
A significant proportion of this wealth is tied up in residential property.
Consider a typical situation.
A retired couple in their early 70s owns a home worth $1.5 million. They have paid off their mortgage and receive the Age Pension, supplemented by modest superannuation savings.
On paper, they are wealthy.
But their everyday finances tell a different story.
They may be carefully managing grocery bills, postponing home improvements or avoiding holidays to preserve their savings.
Meanwhile, their adult children could be struggling with large mortgages, childcare expenses or the challenge of saving for their first home.
The parents want to leave their children an inheritance, but the children may not receive it for another 15 or 20 years.
By then, the financial assistance might be far less valuable than it would be today.
This raises an interesting question:
Could some families benefit more from sharing a portion of their wealth during their lifetime, rather than waiting until it becomes an inheritance?
The Rise of the ‘Living Inheritance’
Traditionally, inheritance occurs after someone passes away.
However, a growing area of interest in family financial planning is the concept of a living inheritance.
This simply means providing financial assistance to children or grandchildren while you’re still alive.
For example, older parents might choose to:
- Help an adult child with a deposit on their first home.
- Assist their children in reducing an expensive mortgage.
- Contribute towards grandchildren’s education.
- Provide financial support during a difficult period.
- Help younger family members establish greater financial security.
The attraction is not necessarily about giving away more money.
It’s about providing financial support when it could make the greatest difference.
For a 35-year-old struggling to enter the housing market, receiving financial assistance today could potentially be more useful than receiving a larger inheritance at age 60.
Of course, any decision to provide a living inheritance needs to be balanced against the parents’ own financial security.
Retirement can last 20 or 30 years, and future healthcare, aged care and living expenses must remain the priority.
This is where understanding home equity becomes particularly relevant.
How Could a Reverse Mortgage Help?
A reverse mortgage is a specialist type of home loan generally designed for homeowners aged 60 and over, although some lenders offer options from age 55.
It allows eligible homeowners to access part of the equity accumulated in their property while continuing to own and live in their home.
Unlike a traditional home loan, there are generally no compulsory regular repayments while the borrower continues to meet the loan conditions.
Instead, interest is added to the outstanding loan balance, which is usually repaid when the property is sold, the borrower permanently moves out, or the estate is settled.
You can learn more in our Guide to Reverse Mortgages.
Example: Helping Children Without Selling the Family Home
Consider a hypothetical couple aged 70 who own their home outright.
Their property is worth $1.4 million, and they would like to help their daughter purchase her first home.
They could potentially use a reverse mortgage to access $100,000 of their home equity and provide this money to their daughter.
This could help her increase her deposit, reduce the size of her mortgage or enter the property market sooner.
Meanwhile, the parents could continue living in their existing home.
However, there is an important trade-off.
The reverse mortgage is a debt, and interest accumulates over time.
For illustration, a $100,000 reverse mortgage at an assumed interest rate of 8% per annum, with no repayments, would grow to approximately:
| Time elapsed | Approximate loan balance |
| Initially | $100,000 |
| After 5 years | $146,900 |
| After 10 years | $215,900 |
| After 15 years | $317,200 |
| After 20 years | $466,100 |
Illustrative figures only. Assumes a constant 8% annual interest rate, annual compounding, no fees, no additional borrowing and no repayments. Actual loan balances will depend on the lender, interest rate, fees and repayment arrangements.
In this example, the parents would have provided $100,000 to their daughter, but the amount ultimately owing against their property could be substantially higher.
That debt would generally reduce the value of their remaining estate.
A reverse mortgage does not create additional family wealth. It allows existing property wealth to be accessed earlier, at a borrowing cost.
Whether this is worthwhile depends on the family’s circumstances, financial goals and alternatives.
Could a Reverse Mortgage Help Families Plan Around a Future Inheritance Tax?
Potentially, but there is an important distinction between legitimate estate planning and speculation about future tax laws.
If Australia eventually introduces an inheritance tax, some families may reconsider how and when they transfer wealth between generations.
However, there is currently no legislation setting out how such a tax would operate.
A future government could introduce rules covering lifetime gifts, estate values, exemptions or other arrangements.
Therefore, taking out a reverse mortgage or giving money to children today should not be regarded as a proven strategy for avoiding a hypothetical future inheritance tax.
There is no guarantee that transferring wealth early would provide any tax advantage under laws that might be introduced in the future.
The more practical opportunity is to consider how home equity could support a family’s existing financial goals.
For some households, that might involve helping children sooner.
For others, it might mean improving their own retirement lifestyle, reducing financial stress or preserving savings for unexpected expenses.
Any significant gifting or estate planning decision should be discussed with qualified legal and financial advisers.
What About Protecting Your Children’s Inheritance?
One of the most common concerns about reverse mortgages is their potential impact on inheritance.
It’s an entirely reasonable concern.
Many older Australians have worked hard to pay off their homes and naturally want to leave something meaningful to their families.
However, taking out a reverse mortgage does not automatically mean there will be no inheritance left.
The outcome depends on several factors, including:
- The amount initially borrowed.
- How long the loan remains outstanding.
- The interest rate and fees.
- Whether voluntary repayments are made.
- How property values change over time.
- Whether additional funds are drawn down.
Some reverse mortgage products also offer features designed to protect a portion of the property’s equity, subject to lender conditions.
Importantly, reverse mortgages taken out in Australia since 18 September 2012 have statutory negative equity protection.
This generally means the borrower or their estate cannot be required to repay more than the property’s market value when the loan is settled in accordance with the relevant legal requirements.
However, this protection does not guarantee that any equity will remain for beneficiaries.
For more information, visit the Australian Government’s MoneySmart guide to reverse mortgages.
Should You Preserve Your Inheritance or Enjoy More of Your Wealth?
For many Australians approaching retirement, this may be the more important question.
There is no single correct answer.
Some retirees place a very high priority on leaving their home, or its full value, to their children.
Others feel that after a lifetime of working, saving and making mortgage repayments, they should be able to enjoy some of their accumulated wealth.
Many want to achieve both.
A reverse mortgage may offer flexibility in certain circumstances.
For example, a homeowner might use a relatively modest amount of equity to fund essential home improvements, medical expenses or additional retirement income.
This could improve their quality of life while retaining substantial equity in their property.
Alternatively, they might choose to provide financial assistance to their children, with the understanding that this could reduce the inheritance available later.
The key is making an informed decision based on personal priorities, rather than feeling pressured to preserve every dollar of property wealth for the next generation.
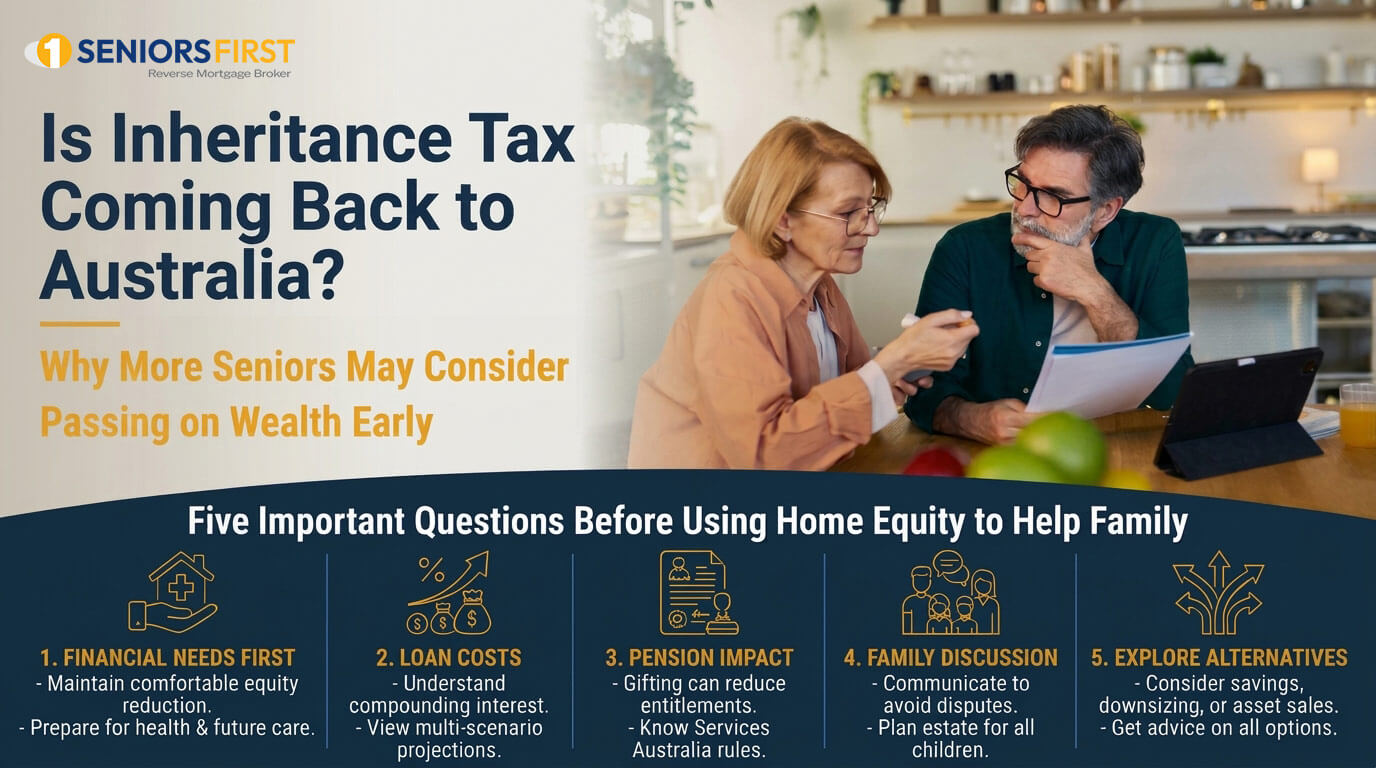
Five Important Questions Before Using Home Equity to Help Family
If you’re considering using a reverse mortgage to assist your children or grandchildren, there are several important questions to discuss.
1. Can I comfortably afford to reduce my home equity?
Your financial needs must come first.
Consider future healthcare expenses, home maintenance, unexpected costs and the possibility of needing residential aged care.
2. How much will the loan cost over time?
Because reverse mortgage interest generally compounds, the outstanding balance can grow considerably over a long period.
Ask for projections showing different interest rate and property growth scenarios.
3. Could the gift affect my Age Pension?
Giving money to family members may affect your Centrelink entitlements.
Services Australia applies gifting rules when assessing certain gifts under the income and assets tests.
The way reverse mortgage proceeds are held or used can also affect your circumstances.
It is important to seek advice before making significant gifts.
4. Have I discussed the decision with my family?
Open communication can help avoid misunderstandings.
If you’re providing financial assistance to one child but not another, consider how this might affect your estate planning arrangements.
5. Are there better alternatives?
A reverse mortgage is only one possible solution.
Depending on your circumstances, alternatives might include using existing savings, downsizing, selling other assets or making different arrangements for financial assistance.
Professional advice can help you understand the advantages and disadvantages of each option.
A New Way to Think About Family Wealth
The renewed debate about inheritance taxes reflects a broader change taking place across Australia.
Older generations hold substantial property wealth, while younger Australians face increasingly difficult financial challenges.
At the same time, many retirees are discovering that owning a valuable home doesn’t necessarily translate into having enough money to enjoy retirement.
These competing pressures are encouraging more families to think differently about how they use and share their wealth.
A reverse mortgage won’t be the right solution for everyone.
But for some older homeowners, it could provide an opportunity to access part of their housing wealth, support their family and improve their retirement lifestyle without immediately selling the family home.
And regardless of whether Australia ever introduces an inheritance tax, the underlying question remains:
Is the best inheritance always the largest amount you can leave behind — or could using some of your wealth during your lifetime create greater benefits for you and your family?
That’s a conversation worth having.
Explore Your Options With Seniors First
At Seniors First, we believe older Australians deserve to understand all their options before making important financial decisions.
Established in 2006, Seniors First specialises in reverse mortgages and later-life lending solutions for Australian homeowners.
Our experienced brokers can help you understand how much equity you may be eligible to access, compare available lending options and explore how a reverse mortgage could affect your future finances and estate.
Whether you’re looking to improve your retirement lifestyle, help your children financially or simply understand your options, we’re here to provide clear, straightforward guidance.
Find out whether a reverse mortgage could be suitable for your circumstances.
Important information: This article provides general information only and does not constitute personal financial, legal or taxation advice. Reverse mortgages involve borrowing costs and can reduce the equity available in your home and estate. Consider your long-term financial needs, seek appropriate independent advice and carefully review the terms and risks before proceeding.
If an inheritance tax comes in I will be first in line for a reverse mortgage. If I’m not allowed to give my children the maximum amount of money through the value of my house then I may as well enjoy myself and spend it all.
The answer is to increase the GST to 15% and reduce taxation and also give pensioners the right to earn extra through work and no income tax on the pension.