What is Reverse Mortgage
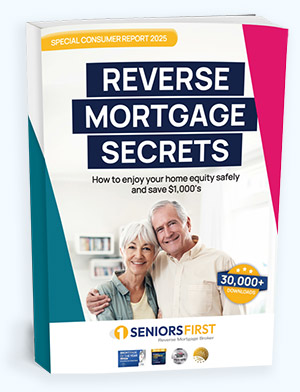
FREE Reverse Mortgage Australia guide from Seniors First. 30,000+ downloads since its first edition in 2008.
What's a Reverse Mortgage loan in Australia?
A Reverse Mortgage is a specialised home loan designed for older homeowners that allows them to access some of the equity in their property without having to sell their home or make regular loan repayments.
It is called a “reverse” mortgage because it works in the opposite way to a traditional home loan. With a traditional mortgage, you make repayments over time and the loan balance gradually reduces.
With a Reverse Mortgage, repayments are generally not required during the life of the loan. Instead, the interest is added to the loan balance over time and the loan is usually repaid later when the property is sold.
Reverse Mortgage loans are specifically designed for over 55's whose wealth is tied up in their home rather than available as income.
Table of Contents
The Role of Home Equity in Retirement
For many Australians, the family home is their largest financial asset. In fact a recent industry report found over 55's have a combined $3 Trillion in untapped home equity.
However, retirement income typically comes from a combination of:
For some retirees, these sources may not provide sufficient income flexibility. A Reverse Mortgage allows homeowners to convert a portion of their home equity into accessible funds without needing to move.
This is sometimes referred to as home equity release.
Home equity release products are designed to help address what economists often describe as the “asset-rich, income-poor” retirement challenge, where a person owns a valuable home but has limited liquid cash flow.
How Reverse Mortgage Repayment Works
At its core, a Reverse Mortgage operates as a secured loan against residential property.
The lender provides funds to the borrower, and the borrower grants the lender a mortgage over their home as security — similar to a standard home loan.
However, the repayment structure is different.
Instead of making monthly repayments of principal and interest, the borrower can defer repayments for the duration of the loan.
Interest is typically capitalised, meaning it is added to the outstanding loan balance periodically (usually monthly).
Over time, this means the total loan balance increases.
The loan is generally repaid when a defined repayment event occurs, such as:
At that point, the property is usually sold and the loan is repaid from the sale proceeds. Any remaining equity belongs to the homeowner or their estate.
Legal Structure of a Reverse Mortgage
Legally, a Reverse Mortgage is structured as a regulated credit contract under NCCP secured by a mortgage over real property.
The borrower remains the legal owner of the property throughout the life of the loan.
The lender does not own the home and cannot force the borrower to sell the property simply because the loan balance increases.
However, borrowers must continue to meet certain obligations, including:
These conditions are similar to those found in traditional mortgage contracts.
Reverse Mortgage Interest Calculation
Interest on Reverse Mortgages typically compounds over time because repayments are deferred.
For example, if a borrower withdraws $100,000 and the interest rate is applied annually, the interest is added to the loan balance rather than paid monthly.
Over time, the interest itself also accrues interest.
This compounding effect is one of the most important aspects borrowers need to understand.
However, many modern Reverse Mortgage products allow borrowers to:
These features can help manage long-term costs.
Government Regulation of Reverse Mortgage
Reverse mortgages in Australia are regulated by the Federal Government under the National Consumer Credit Protection Act (NCCP) and associated consumer credit laws. These laws impose responsible lending obligations on lenders and provide additional protections specifically for Reverse Mortgage borrowers. Key regulatory protections include:
No Negative Equity Guarantee
Australian law requires reverse mortgages to include a No Negative Equity Guarantee (NNEG).
This means borrowers can never owe more than the value of their home when the property is sold.
If the loan balance exceeds the sale price of the home, the lender must absorb the loss.
This protection was introduced to ensure borrowers and their families are not left with debt beyond the property value.
Mandatory Equity Projection Disclosure
Lenders (and brokers) must provide borrowers with projections showing how the loan balance may grow over time.
These projections typically show the estimated loan balance and remaining home equity over a period such as 5, 10, 15, or 20 years.
The purpose is to ensure borrowers understand the potential long-term impact of compound interest.
Independent Legal Advice
Before a reverse mortgage can proceed, borrowers must receive independent legal advice.
This ensures the borrower fully understands:
This requirement is designed to support informed decision-making and protect vulnerable consumers.
Is a Reverse Mortgage a Good Idea?
This is one of the most searched questions in Australia.
The honest answer is:
A Reverse Mortgage can be a very good idea in the right circumstances.
It can also be unsuitable in others. Reverse Mortgages are tools.
Whether they are “good” depends entirely on how and why they are used.
Below we examine some common real-world scenarios.
Reverse Mortgage Suitability: The Traffic Light Guide
General Suitability Summary
Scenario
Reverse Mortgage Suitability
Retiring with debt (staying put)
Pension supplement for living expenses
Home renovations & ageing-in-place
Helping family with money
Borrowing before using super funds
Investing into high risk ventures
Large discretionary lump sum only
The difference between green and red outcomes is usually not the product itself, it is how the loan funds are used. NOTE: this traffic light guide provides just a small sample of loan purposes and use cases. It is general information only and does not constitute financial advice. Contact Seniors First to request a personalised credit assessment.
What Can a Reverse Mortgage Be Used For?
Common uses include:
Paying out existing mortgage debt
Eliminating loan or credit card repayments
Supplementing pension income
Creating a “cash reserve” for emergencies
Home renovations
Medical expenses
Aged care planning
Helping children financially
Most people use Reverse Mortgage loans not because they are in crisis — but to create stability and peace of mind.
Why Reverse Mortgage Is "Later-Life Lending”
Reverse Mortgage loans are part of a specialised category known as later-life lending. Unlike standard mortgages, later-life lending products must account for factors such as:
Because of these complexities, Reverse Mortgages are typically arranged by lenders and brokers with specific experience in this area.
Key Principle: Draw Down Home Equity Gradually
One of the most important strategic principles with Reverse Mortgages is often described as:
Only access the equity you need, when you need it.
Many borrowers choose flexible structures such as a line of credit so they can draw funds gradually rather than taking a large lump sum upfront. We call this the 'Reverse Mortgage Golden Rule'. This approach can significantly reduce long-term interest costs while preserving more equity in the home.
Loan-to-Value Ratios and Age-Based Lending
A general guide to Reverse Mortgage LVR
Age
Typical Maximum LVR
60 years
15-20% of property value
70 years
25-30% of property value
80 years
35-45% of property value
Older borrowers may be able to access a higher proportion of their home equity because the expected loan duration is shorter. Credit criteria varies widely between lenders.
Reverse Mortgage lending limits are generally based on a combination of:
Because the loan may remain in place for many years, lenders typically restrict the loan size relative to the property value.
This is known as the Loan-to-Value Ratio (LVR).
Housing Security and Lifetime Occupancy
One of the key design features of Reverse Mortgages is that borrowers can generally remain living in their home for as long as they choose, provided they meet the basic loan obligations.
This is particularly important in retirement planning because housing stability is often a priority for older homeowners.
Unlike downsizing or selling the family home, a Reverse Mortgage allows borrowers to remain in their existing community, close to family, social networks, and support services.
For many retirees, maintaining housing security is just as important as accessing financial resources.
For many retirees, maintaining housing security is just as important as accessing financial resources.
Reverse Mortgage vs Government Home Equity Access Scheme (HEAS)
The Home Equity Access Scheme (HEAS) is administered by Services Australia. It allows eligible pensioners to access home equity through a loan secured against the home.
Key differences:
Feature
HEAS
Reverse Mortgage
Lump sum option
Limited
Yes
'Income' payments
Yes
Yes
Cash Reserve
No
Yes
Application times
Slower
Faster
Interest rate
Lower
Higher
Maximum access
Capped
Higher potential
'Income' payments are regular, scheduled drawdowns of your home equity on a fortnightly or monthly basis. The Cash Reserve feature is a line of credit with funds at call - great for flexibility.
Each option has advantages. The right choice depends on your goals.
What Are the Pros and Cons of a Reverse Mortgage?
Benefits
Considerations
Reverse Mortgage loans are long-term tools and should be treated as such.
What is a Reverse Mortgage (video)
Why Use a Specialist Reverse Mortgage Broker?
Reverse Mortgages are not standard home loans, they are significantly more complex with potential implications for Age Pension, estate planning, and retirement income. Seniors First are highly experienced specialists:
Most general mortgage brokers do not understand Reverse Mortgage. Only a specialist broker such as Seniors First has deep, first-hand experience of the internal processes and credit criteria of Reverse Mortgage lenders.
When it comes to Reverse Mortgage loans, experience matters - always deal with a specialist broker.
Seniors First has specialised in later-life lending since 2006. We:
There are 150 points of difference between the top four Reverse Mortgage lenders. Seniors First team is one of the few brokers in Australia who can reliably assess which lender is most likely to fund a loan based on property type, location, loan purpose, spending patterns and more.
This information is not publicly available. It’s also highly dynamic; each lender regularly applies changes to their policies and procedures.
In Summary
A Reverse Mortgage is a regulated home loan designed for older homeowners that allows them to access a portion of their home equity without selling their property or making regular repayments.
It sits at the intersection of:
When structured appropriately and used for the right reasons, Reverse Mortgage can provide valuable financial flexibility in retirement while allowing homeowners to remain in their home.
However, like any financial product, it is most effective when used as part of a considered long-term plan.
Rated 4.9 stars on
“Sincere thanks to Andrew and Seniors First .. the loan has been life changing.”

Deborah Collett
Frequently asked questions
Yes it is safe - if you use a recognised Reverse Mortgage lender who is regulated under the NCCP. Some other providers in the market may offer credit or loan-type products that are badged as 'senior's equity release' or 'Reverse Mortgage alternative'. Be wary of these operators. Apply extra scrutiny and due diligence. They are not required to offer the same consumer protections as Reverse Mortgage lenders and brokers.
No. You still own your home. A reverse mortgage is simply a loan secured against your property, similar to a traditional mortgage in that respect. The title remains in your name, and you continue living in your home as the owner.
Yes. Most reverse mortgages allow voluntary repayments with no regular repayment requirement. You can often pay interest, reduce part of the loan balance, or make lump sum repayments when it suits your circumstances. This flexibility can help manage how quickly the debt grows.
Potentially, yes. A Reverse Mortgage does not automatically reduce your Age Pension, but the impact depends on how the borrowed funds are structured and used. For example, money drawn and left in a bank account may count towards Centrelink asset limits. That is why specialist guidance is so important.
Australian reverse mortgages include a No Negative Equity Guarantee. This means that when your home is eventually sold, neither you nor your estate will have to repay more than the sale proceeds of the property, even if the market falls.
In most cases, a reverse mortgage helps people remain in their home for longer. However, you still need to meet the loan conditions, such as living in the property as your main residence, maintaining it, and keeping council rates and insurance up to date. If those obligations are not met, there may be consequences.
Speak With a Reverse Mortgage Specialist
If you would like to understand your options clearly and calmly:
Making financial decisions in retirement should reduce stress — not increase it.
Industry Awards & Recognition
Senior's First has developed a reputation as an award-winning Reverse Mortgage broker, and a trusted name among public policy organisations, the aged care industry, senior’s groups, older borrowers and their families.
Offices
Suite 68, 89-97 Jones St Ultimo NSW 2007
Level 8, 90 Collins Street Melbourne VIC 3000
Level 38/71 Eagle Street Brisbane QLD 4000
Legal
Credit Licence 388952
FBAA Member 104356
© - Seniors First Pty Ltd | Website Design by WebBuzz → 