A line of credit may offer a financial safety net while allowing eligible homeowners to withdraw only what they need.
Groceries, insurance, council rates and medical costs can put pressure on a fixed retirement income. For eligible older Australian homeowners, a reverse mortgage cash reserve — also called a line of credit — may provide access to extra funds without requiring the full amount to be borrowed upfront.
What is a reverse mortgage cash reserve?
A reverse mortgage allows eligible older homeowners, generally aged 60 and over (with some products available from 55), to borrow against home equity while remaining in their home. A cash reserve is an approved facility under certain reverse mortgages from which funds can be drawn as needed.
For example, someone with a $60,000 approved reserve may withdraw $3,000 for dental costs, $5,000 for roof repairs and $2,000 later for another expense. They have drawn $10,000, not $60,000. Interest is generally charged on drawn funds, rather than on the unused reserve, subject to product terms and any applicable fees.
The facility is still debt secured against the home. Availability, drawdown conditions and any lender restrictions must be checked. Read our detailed guide to cash reserves.
Why the feature is popular with older borrowers
According to a Seniors First 2024 survey, 77% of surveyed reverse mortgage borrowers rated a cash reserve option as very important in choosing a lender. Seniors First also reports around eight in ten customers choose a structure combining features such as a lump sum, regular income or cash reserve. These are Seniors First customer figures, not national industry estimates.
The appeal is straightforward: borrowers can plan for uncertain future bills and may not need to borrow more than they currently require.
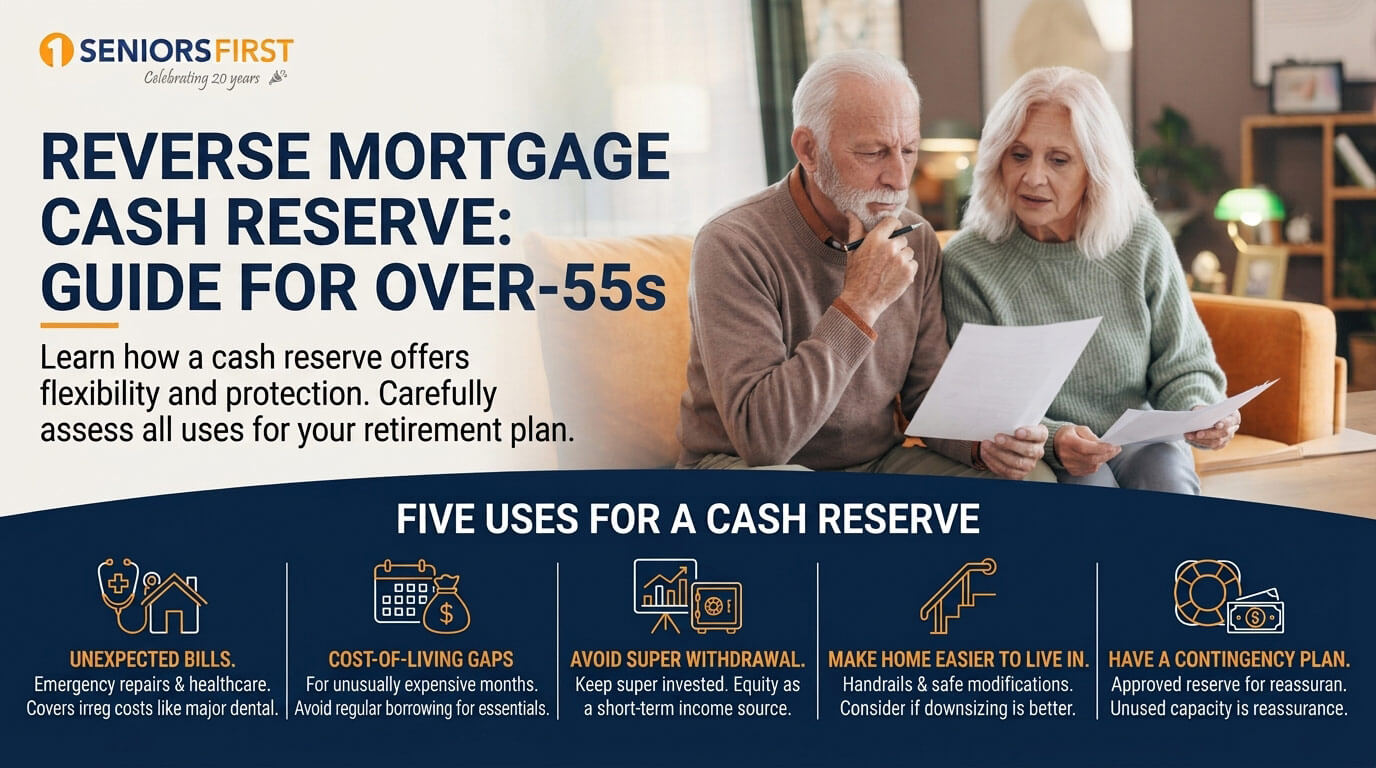
Five possible uses for a cash reserve
1. Unexpected home or healthcare bills
Major dental care, appliance replacements and emergency repairs may be hard to fund from a fortnightly pension. A reserve may offer flexibility to cover irregular costs.
2. Occasional cost-of-living gaps
Accessing an occasional small sum may help with an unusually expensive month. But regularly borrowing for essential living costs can steadily increase debt; this requires careful planning rather than treating the reserve as free income.
3. Avoiding an immediate super withdrawal
Drawing from home equity might allow some super savings to remain invested. Whether that makes financial sense depends on loan interest, investment returns, tax, pension implications and the borrower’s circumstances.
4. Making the home easier to live in
Funds might pay for handrails, a safer bathroom or other home modifications. Borrowers can also consider whether downsizing would be more suitable for their future plans.
5. Having a contingency plan
An approved reserve may provide reassurance that extra money could be accessible for future needs, although unused capacity is subject to the terms of the particular loan.
Why timing withdrawals matters for interest
Reverse mortgage interest commonly compounds over time. At a hypothetical fixed 8% annual rate with monthly compounding, and ignoring fees or repayments, $60,000 withdrawn at once grows to approximately $89,400 over five years. If only $10,000 is drawn and no further funds are used, that debt grows to about $14,900.
These outcomes are different chiefly because different amounts were borrowed; they do not represent a like-for-like comparison of financing the same expenditure. Actual loan rates can change and total costs can be much higher over longer periods.
Borrowers can compare reverse mortgage rates, compare lender features and use the reverse mortgage calculator to explore different scenarios.
Cash reserve, lump sum or regular payments?
Depending on the lender, a reverse mortgage may offer lump sums, periodic payments, a cash reserve or combinations. A lump sum can meet a known major expense; a reserve may be better aligned with unpredictable costs. Different lenders have different eligibility, fee and drawdown rules.
Seniors First explains the different lenders and their features and offers examples in its reverse mortgage case studies, including customers who established reserves alongside refinancing.
Will a cash reserve affect the Age Pension?
An unused credit limit is generally not itself counted as a financial asset for the Age Pension. Once withdrawn, funds may affect means testing depending on what happens to the money. For example, keeping borrowed funds in a bank account can have a different outcome from promptly spending them on home repairs. Ask Services Australia’s Financial Information Service or a qualified adviser about your situation.
Potential risks to understand
- Interest compounds and the debt can grow substantially over time, particularly where no repayments are made.
- Borrowing reduces the equity available for future needs, aged care and inheritance.
- Fees, rates, minimum draws and access to unused funds vary across lenders.
- Age Pension outcomes can depend on how withdrawn money is used or retained.
- Reverse mortgages are secured against your property, so consider whether selling or downsizing later is likely.
For Australian reverse mortgage contracts entered from 18 September 2012, statutory no-negative-equity protection generally limits the amount owed at repayment to the market value of the secured property. It does not prevent erosion of home equity.
Is a reverse mortgage cash reserve right for you?
It may be worth exploring if you have substantial home equity, want to remain at home and need occasional access to extra funds. It may be less appropriate if you plan to move soon, need to preserve equity or face persistent budget shortfalls better addressed in other ways.
Explore all available alternatives, including concessions, a spending review, the government Home Equity Access Scheme, and downsizing. If you are considering a loan, compare total costs rather than only the interest rate.
Find out how a cash reserve could work for you
Seniors First helps eligible older Australians understand cash reserve options, compare lenders and select an appropriate loan structure. Read why specialist advice matters or visit SERAH, our education and support hub for more information.
You can start by using our reverse mortgage calculator or speaking with a Seniors First specialist broker about your circumstances and long-term plans.
Sources and important information
Seniors First, How Does a Reverse Mortgage Work?: https://seniorsfirst.com.au/reverse-mortgage/how-does-a-reverse-mortgage-work/
Seniors First, Cash Reserve for Seniors: https://seniorsfirst.com.au/reverse-mortgage/cash-reserve-for-seniors-the-special-benefits-of-a-reverse-mortgage-line-of-credit/
ASIC Moneysmart: https://moneysmart.gov.au/retirement-income/reverse-mortgage-and-home-equity-release
General information only; not personal financial or legal advice. Actual features and rates depend on lender terms. Reverse mortgages involve fees, accumulating compound interest and reduced home equity. Obtain independent advice and investigate effects on Centrelink and future housing needs.