APRA’s findings are a timely reminder to review your superannuation — and consider your wider retirement funding options.
More than one million Australians are reportedly exposed to superannuation funds identified as financially unsustainable, according to reporting on the Australian Prudential Regulation Authority (APRA) 2025–26 annual report. The reported number has increased 35% year on year. For people aged over 55, the news is a timely reminder to review the savings they may soon rely upon.
What has APRA found?
APRA regulates superannuation trustees and assesses whether funds are delivering appropriate outcomes for members. In its 2026 annual performance testing, 11 platform trustee-directed products and one MySuper product failed their benchmarks. BUSSQ was the MySuper fund named in the reporting.
It is important to distinguish three different issues: a fund failing an investment performance test, a fund facing questions about its future sustainability, and a fund actually becoming insolvent. They are not the same thing. Members should not assume their retirement money has disappeared.
APRA has urged smaller or uncompetitive trustees to address high costs, weak performance and sustainability concerns, which may include improvement programs or consolidation with other funds.
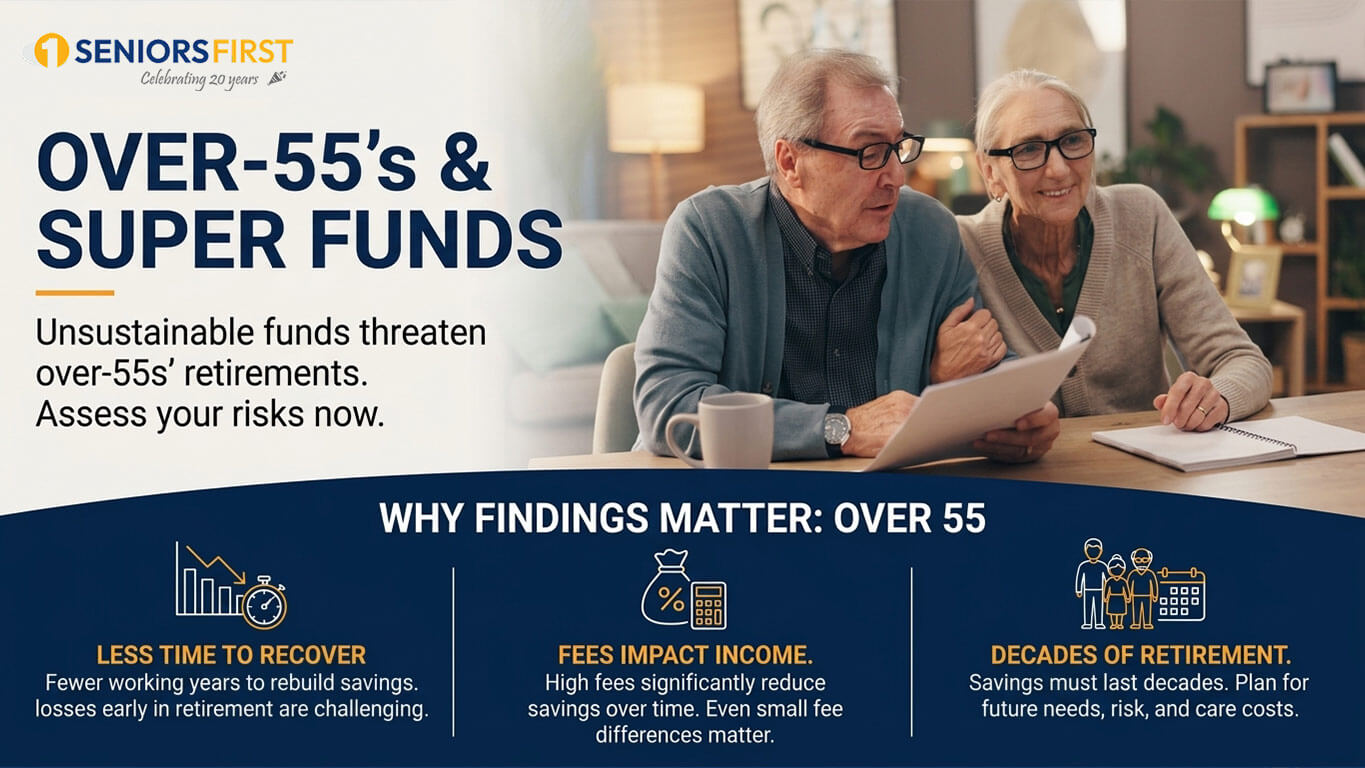
Why the findings matter more when you are over 55
Less time to recover from disappointing returns
Someone approaching retirement may have fewer working years to rebuild savings after a period of underperformance. For people already drawing retirement income, investment losses early in retirement may be particularly challenging.
Fees can make a real difference
On a $300,000 super balance, an extra 1% in annual fees equates to $3,000 in the first year, assuming the balance stays unchanged. Over many years, fees and foregone investment growth can materially affect retirement income.
Retirement may last decades
Australians retiring in their 60s may need their resources to last into their 80s or 90s. Investment decisions should reflect future income needs, risk tolerance, fees and potential healthcare or aged-care costs.
Your family home is another important retirement asset
Some older Australians have substantial wealth tied up in a property yet little spare cash for living expenses. A homeowner might have a valuable house and a relatively modest super balance, leaving them asset-rich but cash-poor.
Options include reviewing expenditure, checking government support, working longer, using savings, downsizing or considering home equity release. The right choice depends on individual circumstances.
Could a reverse mortgage complement superannuation?
A reverse mortgage enables eligible older homeowners to borrow against some of their home equity without selling their home. It generally does not require regular repayments, but interest normally accumulates and compounds, increasing the debt over time.
For suitable borrowers, funds might cover unexpected medical bills, essential home maintenance, or repayment of an existing mortgage. Some products also offer a cash reserve or line of credit so borrowers can withdraw funds as needed rather than taking a larger amount upfront.
That does not mean home equity is automatically a better source of money than super. Reverse mortgage interest is a financing cost, while super returns fluctuate. A decision should account for potential effects on the Age Pension, future housing needs, aged care, estate plans and other options.
A practical example
Imagine a couple aged 67, living in a home worth $950,000, with $250,000 in combined super. They need $35,000 for essential home modifications and are weighing up a super withdrawal against borrowing against their property.
A reverse mortgage could allow them to keep more super invested while funding the improvements, but the loan balance would increase with compound interest. Withdrawing from super avoids that debt but reduces invested savings. Neither is automatically preferable; rates, returns, benefits and their long-term plans all matter.
The Seniors First reverse mortgage calculator can illustrate possible borrowing capacity and loan growth. It is a starting point rather than personal advice.
Five sensible steps to take
- Check your super fund’s long-term performance using APRA information and the ATO YourSuper comparison tool where applicable.
- Review total administration, investment and insurance fees rather than focusing only on headline returns.
- Check whether your investment mix still reflects your retirement date and appetite for risk.
- Seek licensed financial advice before switching funds, especially if you could lose valuable insurance or other benefits.
- Review your full retirement plan, including super, Age Pension, savings and the family home. Consider reverse mortgage versus downsizing alongside other choices.
Your super matters, but it is not your only retirement asset
APRA’s warning is a reason to ask questions, not to make rushed decisions. Australians approaching retirement should understand whether their super fund is competitive and what other resources may support their preferred lifestyle.
Seniors First helps older homeowners compare reverse mortgage lenders, understand lending costs and weigh potential consequences. You can also read our real customer case studies or learn why customers choose our specialist brokers.
Talk through your home equity options
Explore how reverse mortgages work and consider speaking with a Seniors First specialist broker. Separate licensed financial advice is important for superannuation investment decisions.
Sources and important information
AFR (18 October 2026): https://www.afr.com/politics/federal/one-million-australians-in-unsustainable-super-funds-apra-20261018-p616fm
APRA annual report: https://www.apra.gov.au/apra-2025-26-annual-report
APRA 2026 performance package: https://www.apra.gov.au/news-and-publications/comprehensive-product-performance-package-2026-insights-paper
General information only. It does not take account of your circumstances and is not personal financial, investment, taxation or legal advice. Reverse mortgages involve fees, compounding interest and reduced future home equity. Seek appropriate independent advice.