Australia has millions of spare bedrooms, a shortage of suitable homes for younger families, and an ageing population living in properties that may be much larger than they need.
So why aren’t more older Australians selling up and downsizing? The answer is more complicated than many people think.
While downsizing is often presented as an obvious financial decision, new attention on Australia’s housing challenges is highlighting what older homeowners have understood for years: moving to a smaller home isn’t always cheaper, easier or better.
For many Australians aged 60 and over, the decision to stay put can be both emotional and practical.
And increasingly, some homeowners are exploring alternatives that allow them to enjoy retirement without selling the family home.
The Great Australian Downsizing Dilemma
In October 2026, fresh media attention focused on the reluctance of older Australians to downsize, despite growing pressure to free up larger homes for younger families.
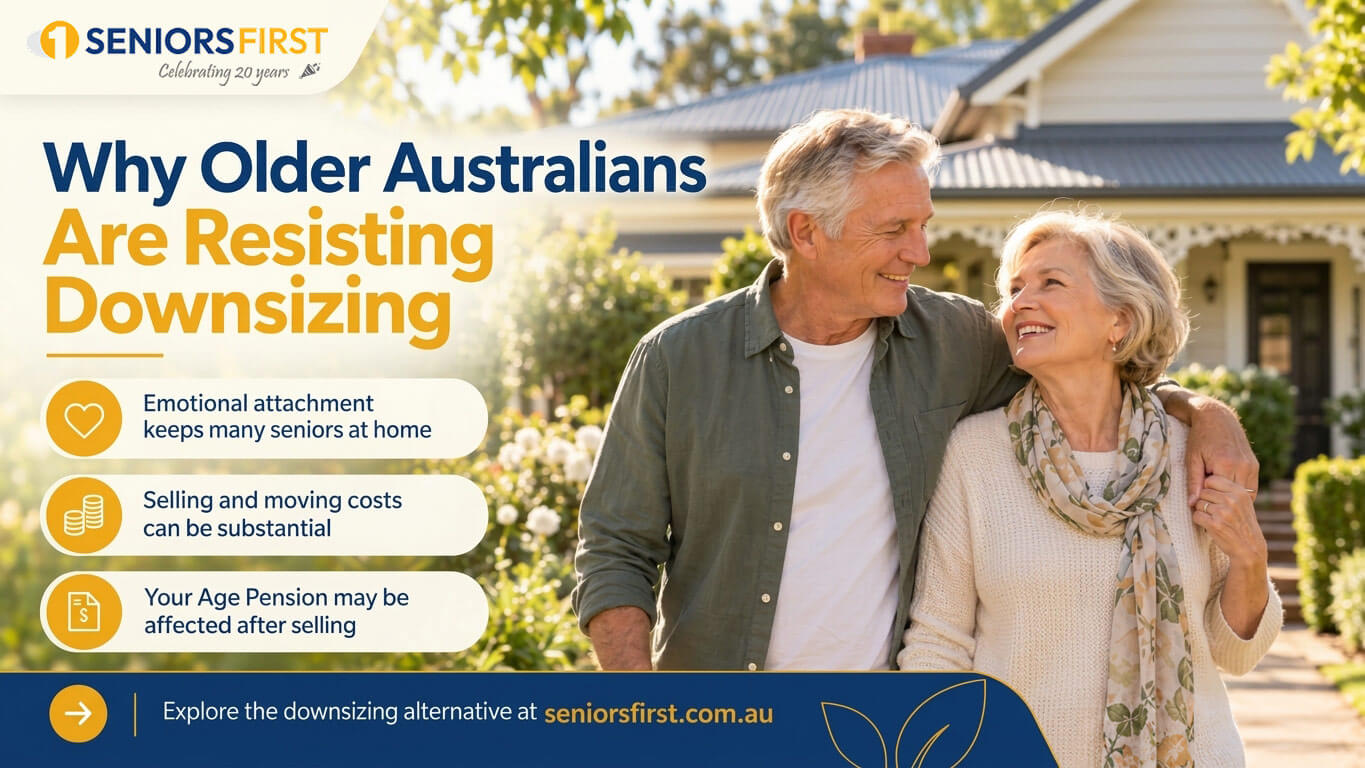
Recent reporting suggested that 64% of Australians over 50 were unlikely to pursue downsizing, with emotional attachment and moving expenses among the major barriers.
The figures highlighted two particularly important concerns:
- Emotional attachment to the family home.
- The substantial costs involved in selling, buying and moving.
These findings reflect an issue that housing researchers have been examining for years.
Research from the Australian Housing and Urban Research Institute (AHURI) has consistently found that older Australians’ housing decisions are driven by far more than property size or potential financial gains.
Source: AHURI – Moving, Downsizing and Housing Equity Consumption Choices of Older Australians
So what’s really stopping people from moving?
1. The Family Home Is More Than Just a Financial Asset
For many older Australians, the family home represents decades of memories. It’s where children were raised, friendships were formed, celebrations were enjoyed and neighbours became lifelong friends. Selling can mean leaving behind much more than bricks and mortar.
AHURI research has highlighted the powerful influence of emotional attachment, familiar surroundings and established community relationships on decisions to move.
For some people, a smaller house might be easier to maintain. But it could also mean leaving their favourite local shops, trusted doctor, neighbours and support networks.
And after 30 or 40 years in the same community, starting again somewhere new isn’t always appealing.
The desire to stay in a familiar home is not necessarily resistance to change. It can be a deliberate lifestyle choice.
2. Downsizing Can Be Surprisingly Expensive
One of the biggest misconceptions about downsizing is that moving to a smaller home automatically releases a large amount of cash.
Sometimes it does. But depending on where you live, the savings can be much smaller than expected.
Consider this hypothetical example.
A couple in their late 60s own a home worth $1.2 million.
They are considering selling and purchasing a smaller property for $900,000. At first glance, the difference is $300,000.
But there are costs to consider.
| Item | Illustrative amount |
| Sale of family home | $1,200,000 |
| Purchase of smaller home | −$900,000 |
| Agent, marketing and selling costs | −$25,000 |
| Stamp duty and purchase costs | −$35,000 |
| Moving and other expenses | −$10,000 |
| Estimated remaining cash | $230,000 |
These are illustrative amounts only. Actual costs vary significantly by state, property value and individual circumstances, and concessions may apply.
For this couple, their apparent $300,000 windfall has reduced to $230,000. That’s still a substantial amount of money. But consider what else has changed.
They’ve moved away from their familiar home, potentially reduced their living space and incurred $70,000 in transaction and moving expenses.
Depending on their financial goals, remaining where they are may deserve serious consideration.
3. Finding the Right Smaller Home Isn’t Easy
Downsizing also assumes there’s a suitable alternative available.
But what if the ideal property doesn’t exist in your preferred neighbourhood?
Many retirees aren’t necessarily looking for a tiny apartment. They may want a comfortable two- or three-bedroom property, a small garden, room for visitors, space for hobbies and easy access to services. They may also need single-level living, accessible bathrooms and minimal maintenance.
Research published by AHURI in 2020 found that only 22% of households surveyed that had downsized moved within their original neighbourhood.
Source: AHURI – Effective Downsizing Options for Older Australians
That suggests downsizing often involves changing communities, not simply moving to a smaller property down the road.
For older Australians who value their local friendships and support networks, that can be a significant drawback.
4. Downsizing Could Affect Your Age Pension
For homeowners receiving the Age Pension, moving can introduce another financial consideration.
Under Australia’s Age Pension rules, your principal home is generally excluded from the assets test.
However, if you sell your home and keep some of the proceeds as savings or investments, those remaining funds may be assessed under Centrelink’s assets and income tests.
Depending on your circumstances, this could reduce your pension.
For example, someone who sells their home and releases $250,000 in additional financial assets may find that their pension entitlement changes.
There are special rules for proceeds intended to purchase, build or renovate another principal home, including temporary assets-test exemptions.
The rules depend on individual circumstances, and the current exemption can generally last up to 24 months, with an extension of up to 36 months in some situations.
Source: Services Australia – Real Estate Assets
The important lesson?
Before downsizing, consider not just how much cash the move could release, but how it might affect your Age Pension, ongoing costs and future financial position.
5. Many Seniors Simply Don’t Want to Move
It’s worth remembering that downsizing isn’t compulsory. And not everyone who lives in a large home feels burdened by it.
Some retirees enjoy gardening, hosting family gatherings and having space for grandchildren to stay.
Others have adapted their homes for ageing in place and see no reason to leave.
In fact, earlier AHURI research found that lifestyle and financial motivations were equally prominent primary reasons for downsizing, each accounting for 27% among the households studied.
Source: AHURI – Effective Downsizing Options
This suggests that retirement housing choices are about much more than money.
For some people, downsizing offers freedom and simplicity.
For others, staying home offers stability, independence and happiness.
Neither choice is automatically right or wrong.
What If You Need More Money But Don’t Want to Downsize?
This is where the conversation becomes particularly interesting.
Some older Australians want to stay in their home but also need additional funds for retirement.
They might be dealing with rising living costs, major home repairs or a desire to enjoy more of their retirement savings.
Traditionally, selling and downsizing has been one way to release money tied up in the family home.
But it’s not the only option.
A reverse mortgage may allow eligible homeowners to access a portion of the equity in their existing property without having to sell it.
In simple terms:
- You remain the owner of your home.
- You can generally continue living there.
- You may be able to access money as a lump sum, regular advances or a flexible drawdown facility, depending on the lender.
- Regular loan repayments are generally not required while you meet the loan conditions.
- Interest is added to the loan balance and compounds over time.
The loan is typically repaid when the property is eventually sold or another repayment event occurs.
For someone who wants to remain at home for another five or ten years, this may provide an alternative worth considering.
Learn more: The Downsizing Alternative
Downsizing vs Reverse Mortgage: What Are the Trade-offs?
Both approaches can provide access to home equity, but they work very differently.
| Consideration | Selling and downsizing | Reverse mortgage |
| Keep existing home | No | Yes |
| Access home equity | Yes | Yes, subject to lending limits |
| Selling and moving costs now | Usually yes | No |
| Ongoing loan interest | Not necessarily | Yes |
| Regular loan repayments | Depends on new financing | Generally not required |
| Impact on future home equity | Depends on property purchased | Loan balance generally grows |
| Potential Age Pension impact | Yes | Yes, depending on funds and circumstances |
| Remain in existing community | Not always | Yes |
A reverse mortgage can provide flexibility, but it is not free money.
Because interest compounds, the debt can grow significantly over time and reduce the amount of equity available for future aged care, downsizing or inheritance.
On the other hand, selling and downsizing can involve substantial transaction costs and may require major lifestyle changes.
The right option depends on the individual’s financial position, housing needs and plans for the future.
What About People Who Want to Downsize — But Not Yet?
There’s another important group of homeowners: those who do want to downsize eventually, but aren’t ready today.
Perhaps they’re waiting until retirement is fully underway. Maybe they want to stay close to grandchildren for a few more years. Or perhaps the right smaller property hasn’t come onto the market.
For some of these homeowners, a carefully structured reverse mortgage may provide temporary financial flexibility.
However, borrowing for a short period may still involve significant costs, and the suitability of a reverse mortgage depends on how soon the homeowner expects to sell.
For homeowners who have already decided to move, specialist bridging finance may be another option to investigate.
Bridging finance can sometimes allow eligible buyers to purchase their next home before selling their existing property. It involves its own costs, lending requirements and risks, including uncertainty about the eventual sale price.
Seniors First provides specialist later-life lending assistance for homeowners considering these options.
Three Questions to Ask Before You Decide
If you’re thinking about downsizing, ask yourself:
- What am I really trying to achieve?
Is your priority to release money, reduce maintenance, move closer to family or find a more accessible property? Different goals may point towards different solutions.
- What will the decision cost over the next 10 years?
Compare the upfront and ongoing costs of selling, buying, remaining at home or borrowing against your equity. Don’t overlook stamp duty, maintenance, interest, changes to Centrelink benefits or the possibility of future aged care costs.
- Which option will give me the lifestyle I actually want?
Retirement is about more than maximising the value of your assets. Feeling secure, staying connected and having enough money to live comfortably are all important. Your home should support the retirement you want, not simply represent a figure on a property valuation.
The Bottom Line: Staying Put Can Be a Rational Choice
The debate about older Australians remaining in large family homes often focuses on housing supply. And making better use of Australia’s existing homes is an important national challenge.
But for individual retirees, the decision is personal. There are legitimate financial, emotional and practical reasons why downsizing may not be desirable.
For some, moving will unlock valuable funds and create a simpler lifestyle.
For others, accessing a portion of their home equity while remaining where they are may be a more suitable alternative.
The important thing is understanding the available options before making a decision.
Love Your Home but Need More Financial Flexibility?
You may not need to sell your home to access some of the wealth you’ve built up in it.
At Seniors First, we’ve specialised in helping older Australians explore reverse mortgages and other later-life lending solutions since 2006.
Our specialist brokers can explain your options, compare lenders and help you understand how accessing home equity may affect your future finances.
Explore the Downsizing Alternative or speak with Seniors First on 1300 745 745.
Disclaimer: This information is general in nature and does not constitute personal financial, legal or taxation advice. Reverse mortgages involve compound interest and may reduce your remaining home equity. Property transactions and home equity release can affect Centrelink entitlements and future financial choices. Seek appropriate independent advice before making decisions.