Reverse Mortgages in Australia
Access home equity without selling your home. We compare lenders for you and explain the costs as clearly as the benefits.
The free reverse mortgage guide
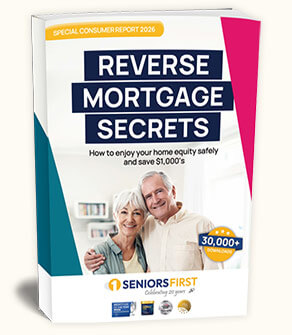
FREE Reverse Mortgage Australia guide from Seniors First. 30,000+ downloads since its first edition in 2008.
A plain-English guide for older homeowners
A reverse mortgage is a loan that lets older Australians borrow money against the equity in their home, with no regular repayments while they live there.
Interest compounds on the loan balance.
It is usually repaid when the home is sold, when you move out permanently (for example into aged care), or after the last borrower dies.
Reviewed by Darren Moffatt, CEO and credit licensee, Seniors First Pty Ltd, Australian Credit Licence 388952. Last reviewed: 18th November 2026
Key Facts
What is a reverse mortgage?
Many older Australians are "asset rich, cash poor": their home is their biggest asset, but retirement income is tight. A reverse mortgage loan turns part of the equity in your home into extra cash, without selling.
Some call it a "backwards mortgage". It is one form of home equity release.
How it differs from a standard home loan
With a standard home loan, monthly repayments reduce the outstanding balance. A reverse mortgage allows you to skip regular repayments, so the interest charged is added to the loan balance, which rises over time.
The debt grows and the net equity in your home falls.
Ways to receive the money
Depending on your age and lender policy, you can take a lump sum, a regular income stream, a line of credit (cash reserve) or a combination. A cash reserve is pre-approved money that generally attracts interest only once drawn, though fees may apply. Regular payments can help with living expenses.
Who owns the home?
You keep full ownership of your home, the lender simply takes a mortgage. Any growth in its capital value over time stays with you. Unless you make regular voluntary payments, interest will compound and the loan balance will grow, leaving you with less net equity when you eventually sell the property.
The loan is regulated credit secured by a mortgage, under the National Credit Code in Schedule 1 to the National Consumer Credit Protection Act 2009. You keep the home repaired and insured and pay the rates, and some lenders require it to stay your main home.
How a reverse mortgage works
The lender lends against your home, and interest compounds over time.
The loan, plus accrued interest and fees, is repaid when:
Any equity left belongs to you or your estate. See how does a reverse mortgage work.
Who can get a reverse mortgage and how much home equity you can access
Reverse mortgages are for Australian homeowners from age 55 with some lenders, and 60 with most. The amount you can borrow is based on the youngest borrower's age. You usually own your home outright, or have a small mortgage the new loan pays out (see paying out an existing home loan), and the property meets the lender's lending criteria for a reverse mortgage loan.
How much you can borrow depends on your age, the value of your home and the lender's policy. Each lender sets a maximum loan to value ratio (LVR), the loan as a share of the property value, and the amount you can borrow increases with age. See how much you can borrow.
Having your home valued
The lender arranges a valuation before approving the loan. Property value, type, location and title can affect the loan amount, and some lenders also look at land size, zoning and postcode. The valuation fee is usually one of the set-up costs.
What a reverse mortgage costs over time
Interest rate, fees and compound interest
Unpaid interest is added to the loan and then charges interest itself. Over time, your debt will grow and your equity will decrease, and the interest rate is likely to be higher than on a standard home loan. See current reverse mortgage rates on our panel.
Fees can include establishment fees, ongoing fees and valuation fees, plus government charges and a discharge fee. Total cost depends on how much you borrow, how you take it, the rate and fees, and how long the loan runs. In Moneysmart's worked example, a couple who borrow to renovate would owe close to half the value of their home after fifteen years, so they borrow less. Try our reverse mortgage calculator.
You may be able to pay interest or make voluntary repayments to slow the debt. You can repay early at any time. Fees vary by lender, and any fixed-rate period can carry break costs. For early repayment fees and other savings, see how to reduce interest on a reverse mortgage.
Why drawing gradually costs less than a large lump sum
Moneysmart notes that "a lump sum will cost more due to compounding interest". Where possible, draw only what you need, gradually as you need it, so that interest accrues potentially on a smaller balance. More equity, and more of your home's future value, is likely to remain. Some lenders let you protect a portion of your home equity too.
Your protections when you take out a reverse mortgage in Australia
Reverse mortgages are regulated credit under the National Consumer Credit Protection Act 2009 and the National Credit Code, with extra protections for borrowers.
Negative equity protection
Reverse mortgages taken out from 18 September 2012 carry a no negative equity guarantee set in law: you won't owe the lender more than your home is worth, as long as you meet the loan terms. Read can you lose your home.
Projections before you go ahead
Before you go ahead, you'll be shown projections of how the loan and your home equity could change over time, using ASIC's Moneysmart reverse mortgage calculator. Brokers provide them before the application is submitted, and again if the loan amount or structure changes before final approval.
Staying in your home
You can remain in your home until you pass away or decide to move out, if you keep to your contract.
Some lenders limit time away or renting the home out.
Independent advice before you sign
Independent legal advice is not a statutory requirement, but it is a mandatory lender requirement. Virtually all lenders require an Independent Legal Advice Certificate before settlement. It protects against elder abuse and ensures you give informed consent. Take your time, talk it through with family and get professional advice.
Loans taken out before 18 September 2012
If your loan is older, check your contract for negative equity protection. If it has none, talk to your lender or get independent advice.
What are the benefits of a reverse mortgage in Australia?
A reverse mortgage allows eligible older Australians to access some of the equity in their home without selling it. Regular loan repayments are generally not required while you continue living in your home and meet the loan conditions.
Like any financial product, reverse mortgages have both advantages and disadvantages. Understanding these can help you decide whether a reverse mortgage is suitable for your circumstances.
Benefit
What it means for you
What are the risks and disadvantages of a reverse mortgage?
Compound interest increases debt
Unpaid interest is added to your loan balance. It is then charged on the growing balance, increasing your debt over time.
Reduced home equity
As your loan balance grows, the equity remaining in your home may decrease, depending on property values.
Reduced inheritance
A growing loan balance may leave less money from your property for your beneficiaries.
Possible Age Pension impacts
How you receive, hold and use the funds may affect Centrelink income and assets tests, depending on your circumstances.
Future repayment obligations
The loan generally becomes repayable when your home is sold, you permanently move out or you pass away. Other conditions may apply.
Higher interest rates and fees
Interest rates may be higher than standard home loans. Establishment, valuation and ongoing fees may also apply.
Variable interest rates
Most reverse mortgages have variable rates. If interest rates rise, your debt may grow faster.
Less flexibility later in retirement
Using equity today may leave fewer funds for future needs, including aged care, downsizing or unexpected expenses.
Other risks to weigh:
ASIC found some borrowers may not have enough equity left for longer-term needs. Weigh up the reverse mortgage pros and cons.
Age Pension and other government benefits
Loan funds you hold as cash or invest may be counted under the Age Pension income and assets tests. How it affects you depends on your circumstances. Check with Services Australia, or book a free appointment with a Financial Information Service officer.
Your principal home is generally not included in the assets test. Read how a reverse mortgage affects your Age Pension.
Moving into aged care
Moving out permanently, for example into care, is a repayment event, and the lender's terms set how long you have to repay. Less equity may be left for care costs. See aged care finance.
Who a reverse mortgage may suit, and who it may not
As general information, it may suit people staying long term with a specific need and no simpler option, who accept leaving less equity. It may not suit people moving soon, wanting to leave the home's full value to family, or able to use savings, HEAS or downsizing.
What should you consider before taking out a reverse mortgage?
Important
Reverse mortgages are secured loans. Interest and fees apply, and the loan must eventually be repaid. Features, eligibility and conditions vary between lenders. This information is general in nature and does not take account of your individual circumstances.
Learn more from ASIC Moneysmart: reverse mortgages and home equity release.
Property obligations
You generally need to maintain your home, keep suitable insurance and pay property-related expenses such as council rates.
Future plans
Consider whether you might downsize, move into aged care or need additional funds later in retirement.
Alternatives
Other options may include downsizing, government assistance or the Home Equity Access Scheme (HEAS).
Independent advice
Financial and legal advice can help you understand the costs, risks, estate implications and suitability of a reverse mortgage.
Long-term loan projections
Ask your lender or broker for projections showing how the debt and remaining home equity may change over time.
Alternatives to a reverse mortgage
A reverse mortgage is one of several ways to access the equity in your home.
Option
RAD
How it works
DAP
May suit
DAP
Trade-off
Reverse mortgage
How it works
a loan, interest added to the balance.
May suit
homeowners staying put.
Trade-off
the debt compounds.
How it works
a government loan, paid fortnightly or as an advance.
May suit
people eligible for a qualifying pension.
Trade-off
compounding interest, payment limits.
Home sale proceeds sharing (home reversion)
How it works
sell a share of the future sale price for cash now.
May suit
people wanting no interest.
Trade-off
the provider gets that share of growth.
Equity release agreement
How it works
sell a portion of your home's value, paying fees from your equity.
May suit
people wanting cash without a loan.
Trade-off
equity can fall to zero.
How it works
sell and move somewhere smaller.
May suit
people ready to move.
Trade-off
moving costs.
Home Equity Access Scheme
The Home Equity Access Scheme (HEAS) is a voluntary, non-taxable loan from the Australian Government for people of Age Pension age who get, or are eligible to get, a qualifying pension. You can take fortnightly payments, an advance lump sum (from 1 July 2022), or both. Combined pension and loan payments can't exceed 1.5 times your maximum pension rate. HEAS loans have a negative equity guarantee, though exceptions may apply. The interest rate is set by the government and published by Services Australia. Compare Home Equity Access Scheme vs reverse mortgage.
Home sale proceeds sharing
(home reversion)
You sell a share of your home's future sale price for a lump sum now. There is no interest, but the provider pays a discounted amount and takes that share at sale, growth included. An equity release agreement is similar, with fees taken from your equity.
Compare home reversion vs reverse mortgage.
Downsizing and other ways to access the equity in your home
Moving somewhere smaller releases cash with no loan, but it costs agent fees, stamp duty, legal fees and moving costs. A local real estate agent can estimate your sale price. Read the downsizing alternative. If you can afford repayments, a home loan top-up or a home loan for older Australians may be an option. Also check your government benefits and other equity release options.
How reverse mortgages differ between lenders, beyond the interest rate
The top four lenders on the Seniors First panel have 150+ points of difference across product features, credit policies and procedures after settlement. ASIC's 2018 review found several providers left the market after the global financial crisis, and the lenders offering these loans have changed over time. See who offers reverse mortgages now.
Product features
Most lenders publish these for their reverse mortgage products: rate type, the comparison rate (it includes most fees and charges), minimum loan amount and maximum amount, LVR by age, minimum property value and ways to access funds. Compare reverse mortgage rates.
Lending criteria and credit policies
Lenders apply credit policies they do not publish, and they change often. They cover cash flow checks, power of attorney, gifting to family, business or investment use, self-employed documents, property restrictions (land size, zoning, postcode, title), debt consolidation and renovations.
Equity access after settlement: top-ups, redraw and cash reserve
What our lender partners say
"I remember when Darren was writing his first reverse mortgages over 20 years ago. Seniors First have since gone on to be the longest running reverse mortgage broker group in the country"
"I remember when Darren was writing his first reverse mortgages over 20 years ago. Seniors First have since gone on to be the longest running reverse mortgage broker group in the country"

Sharon Yardley, Head of Reverse Mortgages, Brighten Home Loans
A Seniors First lender partner (20th anniversary interview, 2026)
helped 7,000+ customers since 2006.
Getting a reverse mortgage through a specialist broker
A broker compares loans from a panel of lenders and handles the application. The lender approves and funds it. As specialist reverse mortgage brokers, we find the lender most likely to approve, structure the loan so interest compounds on less, explain Centrelink and power of attorney issues, and support you beyond settlement.
As mortgage brokers, we must act in your best interests when recommending a loan. This duty has applied to brokers since 1 January 2021. Seniors First introduced its own voluntary code of conduct in 2009, years before the duty became law.
Every situation is different, and your outcome will depend on your circumstances. Read our reverse mortgage case studies.
See also the application process and whether to use a broker or go direct to the lender.
If you're helping a parent decide
The decision belongs to your parent. Talk early about what the money is for, how long they will stay and what will be left. Independent legal advice and a free Financial Information Service appointment help. Researching for a parent? You're welcome to join the call, with their permission. Read what adult children should know.
More Google reviews than any other reverse mortgage broker in Australia as of November 2026
681 Google reviews (20 October 2026)
"At age 86 I was surprised to find that the bank I relied on for eighty years no longer provided reverse mortgages. Although very wary of the web I searched and found Seniors First which appeared well respected."
"At age 86 I was surprised to find that the bank I relied on for eighty years no longer provided reverse mortgages. Although very wary of the web I searched and found Seniors First which appeared well respected."

Ian B.
Frequently asked questions
Compound interest. The longer the loan runs, the faster the debt grows, so your starting age and how much you draw matter. See the pros and cons.
It depends mostly on how much you draw and for how long. Your projections show the likely cost before you commit. Check current reverse mortgage interest rates on our panel.
A reverse mortgage allows you to draw up to your approved limit, and more needs a top-up, which is a new application. For loans from 18 September 2012, the debt can't exceed your home's value if you meet the terms. A cash reserve lets you access equity later.
They are regulated credit with legal protections. ASIC's 2018 review found they help many borrowers meet immediate goals, but borrowers "had a poor understanding of the risks and future costs of their loan". Be wary of unregulated equity release offers.
Both are repayment events. The home is usually sold to repay the loan, and any equity left goes to the borrower or estate. On loans from 18 September 2012 where the terms are met, the estate won't owe more than the home is worth.
Loan funds are not income, so they are generally not taxed. Check your own position with your accountant. For Centrelink, see the Age Pension section above.
Start with the lender's or broker's internal process. Ours is set out in our complaints procedure. If that doesn't resolve it, the Australian Financial Complaints Authority (AFCA) is a free, independent service.
No. Australian reverse mortgages follow the National Credit Code, not United States rules.
Talk it through before you decide
A reverse mortgage gives you cash without selling, at the cost of a growing debt. Compare your options and move at your own pace.
This is general information only and does not take into account your objectives, financial situation or needs. Reverse mortgages involve compound interest and may affect your home equity, Centrelink entitlements, aged care planning and inheritance. Eligibility, rates, limits and terms vary by lender. Consider independent financial and legal advice before you decide.
If a broker fee applies, it will be disclosed upfront in a Credit Quote. See our Credit Guide.
Book a FREE consultation
Have a question about your situation? A specialist broker can explain your options, compare lenders on our panel and walk you through the projections. Researching for a parent? You're welcome to join the call.
Free initial consultation. We're paid by the lender if you go ahead.
Industry Awards & Recognition
Seniors First has developed a reputation as an award-winning Reverse Mortgage broker, and a trusted name among public policy organisations, the aged care industry, senior’s groups, older borrowers and their families.
Offices
Suite 68, 89-97 Jones St Ultimo NSW 2007
Level 8, 90 Collins Street Melbourne VIC 3000
Level 38/71 Eagle Street Brisbane QLD 4000
Legal
Credit Licence 388952
FBAA Member 104356
© - Seniors First Pty Ltd | Website Design by WebBuzz → 