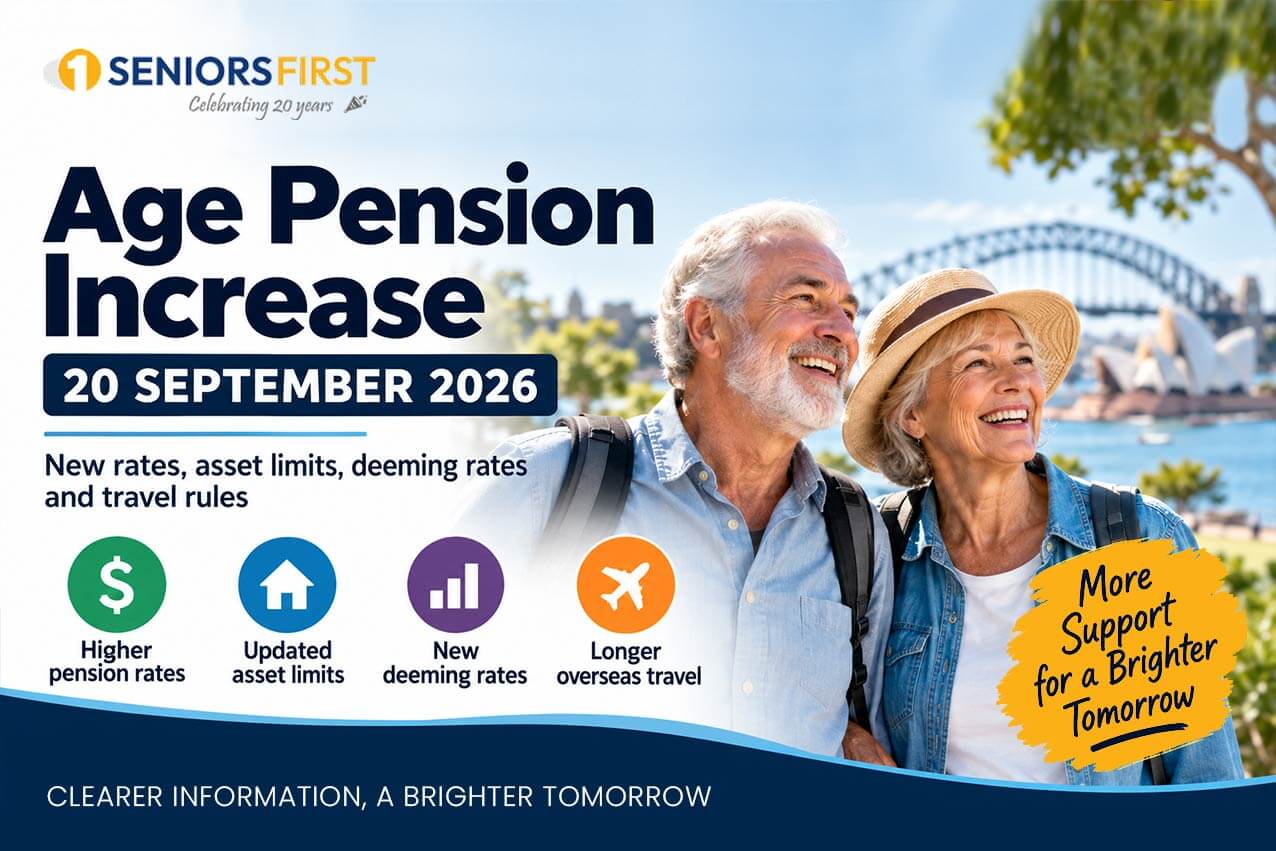
Australian pensioners received an important financial update on 20 September 2026, with higher Age Pension payments and several other changes to Centrelink rules.
The Federal Government says its broader September indexation package will provide additional support to more than 5.3 million Australians, with around $4 billion in additional social security payments flowing through the system.
For Age Pension recipients, there are four changes particularly worth knowing about:
- higher maximum pension payments
- higher cut-off points for some part-pensioners
- increased Centrelink deeming rates
- new rules for the Pension Supplement when travelling overseas
Here is what changed — and what it may mean for your retirement budget.
New Age Pension rates from 20 September 2026
The headline change is an increase to the maximum Age Pension.
From 20 September 2026, the maximum fortnightly payment increased by:
| Age Pension recipient | Increase | New maximum fortnightly rate |
| Single | $36.80 | $1,237.70 |
| Couple — each | $27.80 | $933.00 |
| Couple — combined | $55.60 | $1,866.00 |
The total maximum rate includes the basic pension, maximum Pension Supplement and Energy Supplement. Services Australia says the increases apply automatically, so existing recipients do not need to lodge a new claim.
For somebody receiving the maximum payment, the increase works out to approximately:
Single pensioner: $956.80 extra a year
Couple combined: $1,445.60 extra a year
That is welcome additional income at a time when many retirees are still dealing with higher food, insurance, healthcare, utilities and housing costs.
You can check the current official Age Pension rates through Services Australia. Current Age Pension rates — Services Australia
Age Pension asset cut-off points have increased
There has also been an important change for retirees receiving — or hoping to qualify for — a part Age Pension.
One point is worth clarifying.
The asset limits at which your pension starts to reduce have not increased as part of the September changes. For homeowners, they remain:
- $333,000 for a single person
- $499,000 for a couple combined
For non-homeowners, the corresponding limits are $600,000 and $766,000.
However, because the maximum pension rate has increased, the upper asset levels at which the Age Pension cuts out completely have also moved higher.
New part-pension asset cut-off points
From 20 September 2026:
| Situation | Homeowner | Non-homeowner |
| Single | $745,750 | $1,012,750 |
| Couple combined | $1,121,000 | $1,388,000 |
| Couple separated due to illness, combined | $1,324,500 | $1,591,500 |
These are the standard cut-offs; different circumstances such as receiving Rent Assistance can affect the applicable amount.
This means some Australians who previously sat just above the Age Pension asset-test cut-off may now qualify for a small part pension, assuming they meet the income test and other eligibility requirements.
That may be worth checking, particularly because Age Pension eligibility can also provide access to other concessions.
Check the official Age Pension assets test — Services Australia
But Centrelink deeming rates have also increased
The September changes are not all increases.
From 20 September, the Government also increased the Centrelink deeming rates used to calculate assumed income from financial investments.
The new rates are:
- 75% on financial assets up to the deeming threshold
- 75% on financial assets above the threshold
The applicable thresholds are $66,800 for singles and $110,600 for couples combined.
What is deeming?
Instead of assessing exactly how much income you earn from every bank account or investment, Centrelink assumes that certain financial assets earn a specified rate of return.
Financial assets can include things such as:
- bank accounts
- term deposits
- shares
- managed investments
- some account-based retirement income streams
This deemed income is then included in the Age Pension income test.
An example
Consider a single pensioner with $200,000 of financial assets.
Using the previous deeming rates of 1.25% and 3.25%, deemed annual income would have been approximately $5,164.
Under the new 1.75% and 3.75% rates, the same $200,000 produces approximately $6,164 of deemed income.
That is an additional $1,000 of assessable income each year.
It does not necessarily mean their pension will fall by $1,000. The actual effect depends on their other income, assets and which means test determines their payment.
But for some part-pensioners with substantial savings and investments, higher deeming could offset some of the benefit of the September pension increase.
Read the Services Australia deeming update
Going overseas? The Pension Supplement rules have changed
Another significant change affects pensioners travelling overseas.
Previously, people temporarily leaving Australia generally received their full Pension Supplement for up to six weeks.
From 20 September 2026, that period has doubled.
People travelling temporarily outside Australia can now continue receiving the full Pension Supplement for up to 12 weeks. After 12 weeks, the Pension Supplement stops.
This may be useful for older Australians taking extended holidays or spending longer periods visiting family overseas.
However, it is important to understand that this change specifically relates to the Pension Supplement.
Your main Age Pension has separate overseas-travel and residency rules, so a 12-week holiday should not automatically be interpreted as a guarantee that every component of your Centrelink entitlement remains unchanged.
For people leaving Australia permanently, the Pension Supplement now stops when they leave.
Check Pension Supplement overseas travel rules
Are pensioners actually better off?
For a full-rate Age Pension recipient with relatively modest financial assets, the September increase provides a straightforward boost.
A single full-rate pensioner receives almost $957 more a year, while a couple combined receives about $1,446 more.
For some part-pensioners, however, the picture can be more complicated.
The higher maximum rate increases some asset and income cut-off points, while higher deeming rates may increase assessable income from financial assets.
Your individual outcome therefore depends on much more than the headline pension rate.
It is worth checking your Centrelink account rather than assuming the advertised maximum increase is the amount you will personally receive.
Why the Age Pension is only one part of retirement funding
These changes also highlight a broader issue facing many older Australians.
A retiree can own a valuable home while having relatively little disposable income.
Your principal residence is generally excluded from the Age Pension assets test, meaning some retirees can have substantial wealth tied up in their property while relying heavily on the pension and savings for everyday cash flow.
For homeowners aged 55 and over, one option that may be worth investigating is accessing a portion of that housing wealth using a Reverse Mortgage.
A Reverse Mortgage allows eligible older homeowners to release equity from their property without having to sell their home or generally make regular repayments.
Learn how Reverse Mortgages work in Australia — Seniors First
However, Centrelink treatment is important.
Money released from a home and then retained as cash or invested can potentially become assessable under Centrelink rules. The outcome can differ depending on how funds are used.
For that reason, the objective should usually be to carefully plan how much equity is released, when it is released and what it will be used for, rather than simply borrowing the maximum available.
What should Age Pensioners do now?
There are several practical steps worth considering after the September changes.
First, check your new payment through your Centrelink online account or Express Plus Centrelink app.
Second, if you previously missed out on the Age Pension because your assets were only slightly above the cut-off, check your position again under the new limits.
Third, if you hold significant financial assets, review how the higher deeming rates affect your Centrelink income test.
And if you are planning an overseas trip longer than six weeks, familiarise yourself with the new 12-week Pension Supplement rules before leaving Australia.
Finally, look beyond Centrelink alone.
If your pension and other retirement income are consistently falling short of your expenses, it may be time to review your wider retirement funding options.
Considering using home equity in retirement?
For older homeowners, home equity can potentially provide another source of retirement funding.
Seniors First specialises in helping Australians aged 55 and over understand and compare Reverse Mortgage options from multiple lenders.
You can begin by using the Seniors First Reverse Mortgage Calculator to model how different loan amounts could affect your future loan balance and remaining home equity.
Try the Seniors First Reverse Mortgage Calculator
Or, if you would prefer to learn at your own pace first, SERAH™ — the Seniors Equity Release Access Hub — provides education, tools and support designed specifically for older Australians exploring home equity release.
This article contains general information only. Centrelink entitlements and the treatment of financial assets depend on individual circumstances. Check your personal position with Services Australia and seek appropriate professional advice before making financial decisions.