New research reveals that just 28% of Australians approaching retirement feel financially prepared. But for older homeowners, there may be more options available than they realise.
Australians are becoming increasingly worried about their financial future, with retirement confidence falling to its lowest level in a decade.
According to the newly released 2026 Retirement Income Report from Brighter Super and Investment Trends, just 28% of pre-retirees feel financially prepared for retirement, down from 38% in 2025.
The findings, reported by SBS News on 11 November 2026, reveal that the financial pressure is not limited to people approaching retirement. Australians who have already retired are also finding it increasingly difficult to make ends meet.
For many older Australians, the traditional retirement plan — pay off the mortgage, build up superannuation and live comfortably on retirement savings and the Age Pension — is becoming harder to achieve.
But there is some good news, particularly for people who own their home.
Even if your superannuation balance is smaller than you hoped, there may be practical ways to improve your retirement cash flow without necessarily selling your home.
Retirement confidence in Australia: What the latest research reveals
The Brighter Super and Investment Trends research surveyed more than 4,000 Australians aged 40 and over in August and September 2026.
Its findings paint a concerning picture of retirement preparedness.
| Retirement confidence indicator | 2025 | 2026 |
| Pre-retirees who feel prepared for retirement | 38% | 28% |
| Retirees who say they are living comfortably | 58% | 38% |
| Retirees confident they have enough money to fund retirement | 60% | 41% |
| Retirees just covering basic expenses or struggling | 14% | 30% |
Perhaps most concerning, 54% of pre-retirees expect their retirement income to fall short of their needs.
The rising cost of living is a major reason. Around three-quarters of those surveyed identified inflation and everyday expenses as significant pressures on their financial position.
The research also found that nearly half of pre-retirees expecting a shortfall plan to reduce their spending in retirement.
In other words, many Australians are preparing to lower their expectations rather than exploring ways to improve their financial position.
Source: Brighter Super and Investment Trends 2026 Retirement Income Report.
The retirement dilemma: Asset-rich but cash-poor
For many Australian homeowners aged over 60, the retirement challenge is not necessarily a lack of wealth.
It’s a lack of accessible income.
Consider a couple in their late 60s who own a home worth $1.2 million but have relatively modest superannuation savings.
On paper, they may have substantial wealth. Yet their everyday spending still depends on their Age Pension, superannuation withdrawals and other savings.
With groceries, electricity, insurance, council rates and healthcare expenses continuing to rise, their available income may no longer stretch as far as it once did.
This situation is sometimes described as being asset-rich but cash-poor.
The important distinction is that home equity and retirement income are not the same thing. Your home can be a valuable asset, but it generally doesn’t produce money you can spend unless you sell it, rent part of it out or access some of its equity.
Fortunately, there are several options worth investigating.
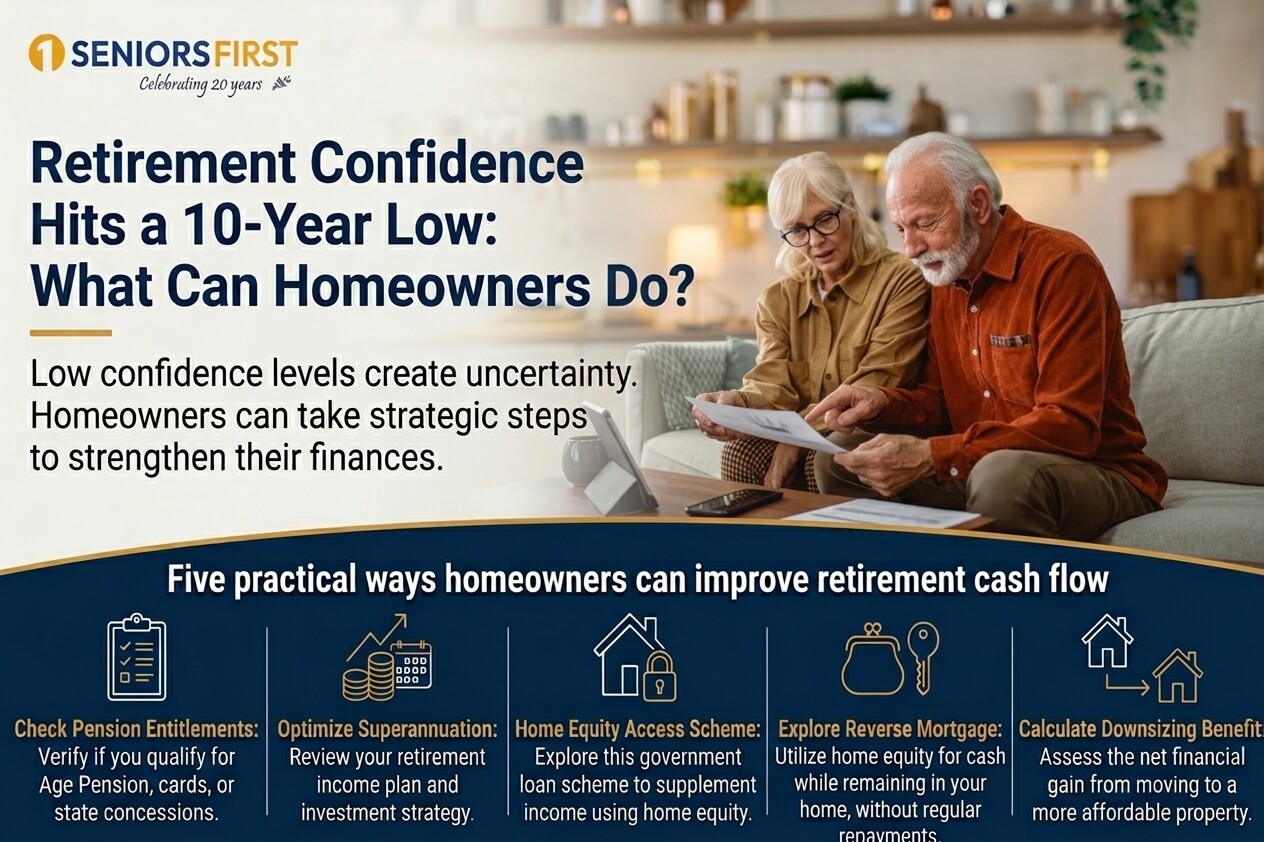
Five practical ways homeowners can improve retirement cash flow
1. Check whether you’re receiving all your Age Pension entitlements
Before considering any form of borrowing, it’s worth checking whether you are receiving the government support you’re entitled to.
Many Australians assume that owning a valuable home means they cannot qualify for the Age Pension.
However, your principal home is generally exempt from the Age Pension assets test, although different thresholds apply to homeowners and non-homeowners.
Depending on your circumstances, you may qualify for a full or part Age Pension, even if your home is worth a substantial amount.
It’s also worth checking your eligibility for additional support, such as:
- Commonwealth Seniors Health Card
- Pensioner Concession Card
- State-based energy and council rate concessions
- Other government rebates and assistance
If you haven’t reviewed your entitlements recently, changes to your savings, income or financial circumstances could make a difference.
Where to start: Visit Services Australia or speak with a Centrelink Financial Information Service officer.
2. Review how you’re using your superannuation savings
Superannuation remains an important source of retirement income, but the way you access it can make a significant difference to your long-term financial position.
For example, some retirees withdraw more than they need from their superannuation accounts, while others are reluctant to use their savings because they’re worried about running out of money.
Finding the right balance is important.
A retirement income review with a qualified financial adviser can help you understand:
- How long your superannuation might last under different withdrawal scenarios
- Whether your current pension account is appropriate
- How your investments are structured
- Whether there are opportunities to improve your retirement income
- How your superannuation and Age Pension work together
The latest Brighter Super research reinforces the potential value of advice.
Among pre-retirees, 43% of those receiving financial advice felt prepared for retirement, compared with 22% of those not currently open to advice.
While these results don’t prove that advice alone causes greater confidence, they highlight the value of understanding your options.
The goal is not simply to save more money. It’s to make informed decisions about the money you’ve already accumulated.
3. Consider the Government’s Home Equity Access Scheme
Many older homeowners are unaware that the Australian Government offers a way to supplement retirement income using home equity.
It’s called the Home Equity Access Scheme (HEAS), formerly known as the Pension Loans Scheme.
Under this scheme, eligible older Australians can receive additional payments secured against Australian real estate.
The scheme may be worth considering if you:
- Have reached Age Pension age, or qualify through an eligible partner
- Own suitable Australian real estate
- Want to supplement your regular retirement income
- Are comfortable using a portion of your property equity to fund retirement
Importantly, you don’t necessarily need to be receiving the Age Pension to qualify.
HEAS payments are loans, not additional pension entitlements or grants. Interest accumulates on the amount borrowed, and the debt must eventually be repaid.
The scheme also has limits on how much can be borrowed, including restrictions on regular fortnightly payments and lump-sum advances.
It can be particularly useful for eligible retirees who want a modest, regular boost to their income.
Learn more: Services Australia – Home Equity Access Scheme
4. Explore whether a reverse mortgage could help unlock home equity
For homeowners aged 60 and over — and from age 55 with some lenders — a reverse mortgage may offer another way to improve retirement cash flow.
A reverse mortgage is a special type of home loan that allows eligible older homeowners to access some of the equity in their property while continuing to live there.
Unlike a conventional home loan, regular mortgage repayments are generally not required while you continue living in the property and comply with the loan conditions.
Instead, interest is added to the loan balance over time, and the loan is usually repaid when the property is sold, the borrower permanently moves out or the estate is settled.
Depending on the lender and your circumstances, funds may be available through:
A lump sum: Useful for paying off an existing mortgage, essential home repairs or other major expenses.
Regular payments: Additional cash flow to help meet living expenses.
A cash reserve or line of credit: Access to funds when needed, rather than borrowing the full amount upfront. Generally, interest is charged only on amounts actually drawn, subject to the lender’s terms and fees.
For example, a retired couple who still have a conventional mortgage might consider refinancing to a reverse mortgage to remove their required monthly repayments.
Alternatively, a homeowner who has paid off their mortgage might establish a small cash reserve to help cover unexpected expenses.
The potential benefit is greater financial flexibility without immediately having to sell the family home.
However, reverse mortgages also involve important trade-offs.
Interest generally compounds over time, increasing the loan balance and reducing the equity remaining in your property. This could affect your future downsizing plans, aged-care funding or inheritance.
There may also be implications for Centrelink payments, depending on how borrowed funds are used.
That’s why it’s important to compare lenders, understand the long-term costs and consider whether borrowing is appropriate for your circumstances.
Learn more: How Does a Reverse Mortgage Work?
You can also use the Seniors First Reverse Mortgage Calculator to explore indicative borrowing amounts and future loan costs.
5. Consider downsizing — but calculate the true financial benefit
For some homeowners, moving to a smaller or less expensive property can provide a practical way to free up retirement savings.
Selling a larger family home and buying a more affordable property may allow you to release equity without taking on a new loan.
There may also be savings from lower maintenance, council rates and other ongoing household expenses.
However, downsizing is not always as financially beneficial as it first appears.
Before making a decision, it’s important to account for:
- Real estate agent fees and selling costs
- Stamp duty and legal fees on the replacement property, where applicable
- Moving expenses
- Renovations or alterations to the new home
- The possible impact on Age Pension entitlements
There are also important lifestyle considerations.
Many Australians have strong emotional connections to their family home, neighbourhood and community. Moving away from familiar surroundings may not be desirable, particularly later in life.
For this reason, downsizing should be considered alongside other options, rather than viewed as the only solution to a retirement income shortfall.
For homeowners who do decide to move, specialist bridging finance may also be worth investigating if they want to purchase their next home before selling their current property.
Which retirement cash-flow option might be right for you?
There’s no single solution that suits everyone.
The most appropriate approach depends on your age, income, savings, property value, existing debts and long-term goals.
| Option | Potential benefit | Important consideration |
| Age Pension and concessions | Increase income or reduce living costs without borrowing | Eligibility and means-testing rules apply |
| Superannuation review | Make better use of existing retirement savings | Withdrawals affect how long savings may last |
| Home Equity Access Scheme | Supplement retirement income using property equity | Loan limits apply and interest compounds |
| Reverse mortgage | Access home equity without generally requiring regular repayments | Debt increases over time, reducing future equity |
| Downsizing | Release capital without necessarily taking on new debt | Transaction costs, lifestyle changes and possible Centrelink impacts |
In some circumstances, a combination of strategies may be appropriate.
The important thing is to understand the costs, benefits and long-term implications before making a decision.
Don’t let retirement anxiety prevent you from exploring your options
The 2026 retirement confidence figures are concerning, but they shouldn’t be viewed as a prediction of what your own retirement will look like.
Every household’s financial circumstances are different.
For people approaching retirement, the best time to start planning is before financial pressure becomes overwhelming.
For those already retired, there may still be opportunities to improve cash flow, reduce expenses or make more effective use of existing assets.
And for Australian homeowners, one important consideration is the potential role of home equity.
Your home may represent decades of hard work and accumulated wealth. Understanding whether some of that wealth could safely support your retirement is worth exploring.
You don’t necessarily need to sell the family home or dramatically reduce your lifestyle to improve retirement cash flow.
But you do need to understand the options available and choose the approach that is right for you.
Find out whether your home equity could help
At Seniors First, we’ve specialised in reverse mortgages and later-life lending since 2006.
Our specialist brokers help older Australians understand their home equity options, compare available lenders and assess the long-term implications of borrowing.
Whether you’re looking to supplement retirement income, pay off an existing mortgage or establish a cash reserve for unexpected expenses, we can help you explore what’s possible.
Explore your options with Seniors First.
- Try our Reverse Mortgage Calculator
- Contact Seniors First for a consultation
- Or call 1300 745 745 to speak with our team.
There’s no obligation to proceed with a loan. The first step is simply understanding your options.
Important information: This article provides general information only and does not take into account your personal financial circumstances, objectives or needs. A reverse mortgage or other home equity loan may not be suitable for everyone. Interest and fees can accumulate, reducing the equity remaining in your property. Consider independent financial and legal advice and check any Centrelink implications before making a decision.