How do Reverse
Mortgages work?

How Reverse Mortgage Works in Australia

A Reverse Mortgage is a loan designed for Australian homeowners aged 55 and over. It lets you unlock equity from your home without selling or moving. Unlike a standard mortgage, you don’t make monthly repayments. Instead, the amount borrowed plus any accrued interest and fees are repaid when you sell your home, move permanently into aged care, or pass away.

This can provide a much-needed financial buffer in retirement to cover living costs, medical expenses, home improvements, or even just peace of mind.

Table of Contents

What is a Reverse Mortgage? (Simple Definition)

Reverse Mortgage is a type of loan where you borrow against the value of your home. You remain the legal owner and can stay in the property for life, provided you meet basic obligations like paying council rates, home insurance, and maintaining the property.
Key takeaway

You don’t need to make regular repayments on Reverse Mortgages. The loan plus any accrued interest and fees is paid back when the property is eventually sold.
Eligibility and Borrowing Limits

Reverse Mortgages are only available if:

  • You’re 55 years or older.
  • You own your home in Australia.
  • The property meets lender requirements (location, condition, and minimum value).

Borrowing Limits by Age

The amount you can borrow increases as you age.
  • At 60 years old: roughly 15–20% of the home’s value.
  • Each year older: borrowing capacity rises by ~1%.
  • At 80 years old: up to 35–45% of the home’s value.

Example: On a $900,000 home, a 65-year-old might access $180,000, while a 75-year-old may access $270,000.

Common Loan Purposes

Many Australian seniors use a Reverse Mortgage to improve quality of life in retirement.
The funds are flexible and can be used for almost anything, but the most common purposes include:

Supplementing retirement income

Covering everyday bills and living expenses, or for "life's little luxuries".

Debt repayment

Clearing mortgages, credit cards, or personal
loans to reduce financial stress.

Medical and aged care costs

Paying for in-home support, equipment, or aged care accommodation.

Family support

Gifting money to children or grandchildren, such as helping with education or a house deposit.

Home improvements

Upgrading kitchens, bathrooms, or making the home more accessible (ramps, rails, modifications).

Lifestyle and travel

Enjoying retirement by funding the purchase of a new car, holidays or hobbies.

Key takeaway

A Reverse Mortgage can provide financial freedom now, but always consider how borrowing now may reduce future options.

How You Can Receive the Funds

Reverse Mortgage loans offer flexibility in how you can draw down the money:

1. Lump sum - take a one-off cash amount, upfront.

Lenders can provide you a lump sum money at the start of your loan. Policies between lenders vary, but some have a minimum drawdown for this option of $10,000, unless you are planning to use the money for in-home aged care. On top of the lump sum, you can receive the proceeds as needed through the other available options.

PERFECT FOR: This option is ideal for debt consolidation, home loan refinance, home renovation, new car purchase, medical expenses.

2. Regular instalment plan (income stream) – receive ongoing monthly or quarterly instalments over time.

Receiving regular advances is ideal if you are planning to draw on your loan gradually, to supplement your retirement income. This option will allow you to set a regular drawdown payment (monthly, quarterly, or yearly) for up to 10 years.

The regular amount you receive feels like 'income' but it is actually a small portion of your home equity. You can set the amount you receive from hundreds, to thousands of dollars each month. The limit is determined by the value of your home, your age and the term schedule.

PERFECT FOR: ‘topping up’ the Age Pension or limited retirement income to better cover living expenses, or for home care costs.

3. Cash reserve / line of credit – set aside a pool of funds you can access later if needed.

You can unlock your home equity to set up a cash reserve that you can easily access anytime you want. The good thing about this option is that you will only pay interest on the cash drawn, as you draw it down.

Depending on the lender, there may be no minimum drawdown amount on a cash reserve facility. Some lenders even allow you to access this money directly by debit card at ATM's.

PERFECT FOR: ‘rainy day’ funds for emergencies and unexpected expenses, or occasional special treats such as holidays.

4. Combination – mix lump sum, income, and cash reserve to suit your situation.

A combination reverse mortgage is very popular. About 8 in 10 Seniors First customers choose some form of combination of lump sum, cash reserve or income stream for their reverse mortgage loan structure.
According to a Seniors First survey in 2024, 77 per cent of Reverse Mortgage borrowers rate the importance of a cash reserve option as 'very high' in their choice of lender.
No Regular Repayments: How It Really Works

One of the biggest advantages of a Reverse Mortgage is that no regular repayments are required.

  • How it works: Instead of paying monthly instalments, the interest is simply added to your loan balance (capitalised).
  • When you repay: The full balance (loan + interest) is only due when you sell your home, move into aged care, or pass away.
  • Optional repayments: Most lenders do allow voluntary repayments at any time, which can help reduce the compounding effect of interest.

Key takeaway

“No repayments” does not mean the loan is free. The debt grows over time due to compound interest (unless you pay monthly interest).
How Interest Calculation Works (Compounding Effect)

Interest on a Reverse Mortgage is calculated daily and 'capitalised', which means the monthly interest charge is added onto the existing loan balance. Over time, this causes the balance to grow faster than with a traditional loan.

  • Example: If you borrow $100,000 at 7% interest, after 10 years (with no repayments), the debt may grow to around $200,000.  
  • Because there are no regular repayments, the effect of compounding is stronger (however you can make voluntary repayments at any time, which will slow this effect)

The biggest drawback of Reverse Mortgages is the compounding interest, which reduces the equity in your home over time. However, it’s important to understand that the home value should also compound over time, and that future capital gains on property may partly, or fully, offset interest costs. CoreLogic reports that Australian home values surged 39.1% in the five years to 2025, representing an increase in the average home value of $230,000.

How to save interest:

Reverse Mortgage Golden Rule
It’s little known that borrowers can enjoy very substantial interest savings on Reverse Mortgage loans by structuring the loan in certain ways. 

In fact, there is what we call the "Reverse Mortgage Golden Rule": draw as much of the loan as possible, gradually over time  (instead of as an upfront lump sum).

This principle is the foundation for our Home EquiSaver™ method, exclusive to Seniors First. 

Home EquiSaver™ is the approach Seniors First brokers use to find the optimal loan structure for each borrower in order to achieve two key objectives:
  • Fulfil the personalised funding needs of the individual borrower, whilst ALSO;
  • Minimising the long-term interest cost in order to preserve more home equity 

The output of the Home EquiSaver™ method is the Compound Interest Savings Ratio (CISR). This ratio is expressed as a percentage of the total potential interest savings that the loan structure could deliver, compared to the interest cost that would otherwise apply on a full lump sum loan. 

The Compound Interest Savings Ratio (CISR) is different for each borrower, depending on the proportion of total loan funds that is taken as an upfront lump sum, versus gradually over time. The higher the ratio, the more interest cost potentially saved  - and the more benefit derived from Home EquiSaver™ to the borrower.

To provide the most meaningful results the following assumptions apply:

  • For illustration purposes, the calculation is done over a 10 year term with a prevailing market interest rate  (note: most Reverse Mortgages actually have no set term) 
  • Any funds not drawn as an upfront lump sum (such as cash reserve and instalment plan funds) are assumed to be drawn monthly in equal instalments

Home EquiSaver™ Example 1:

Total loan facility amount: $100,000

Interest rate: 8% Term: 10 years* 

*Most Reverse Mortgages have no set term, this is for illustration purposes only.

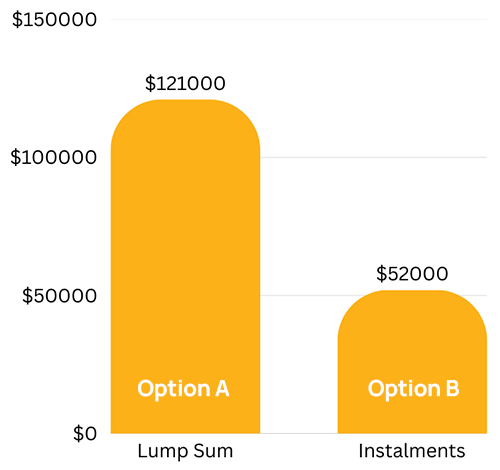
Option A: take all funds as upfront lump sum - $121,000 interest cost (over 10 years)

Option B: take all funds as Instalment plan - $52,000 interest cost (over 10 years)

Net interest saving (NIS) with option B: $69,000 

Compound Interest Savings Ratio (CISR): 57% in potential savings with this loan structure

Compound Interest Savings Ratio (CISR)
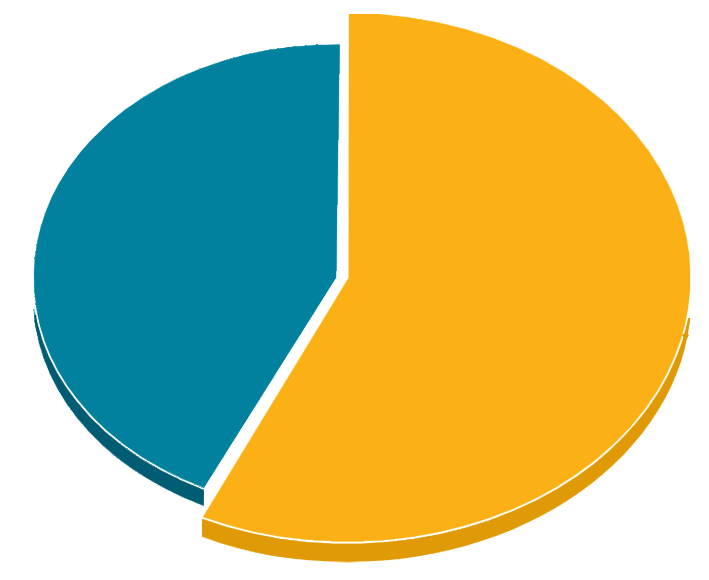
I

57%
SAVED (CISR)

*less interest

Interest Cost Comparison
(10 years)
Home EquiSaver™

Example 2:

Total loan facility amount: $100,000

Interest rate: 8% Term: 10 years*

*Most Reverse Mortgages have no set term, this is for illustration purposes only

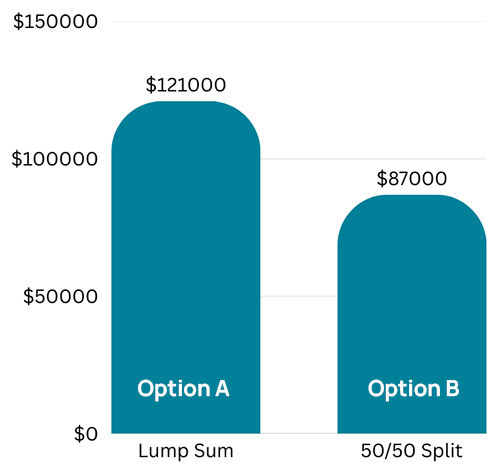
Option A: take all funds as upfront lump sum - $121,000 interest cost (over 10 years) 

Option B: draw $50,000 as a lump sum and $50,000 as instalment plan - $87,000 interest cost (over 10 years) 

Net interest saving (NIS) with option B: $34,000 

Compound Interest Savings Ratio™ (CISR): 28% in potential savings with this loan structure

Compound Interest Savings Ratio (CISR)
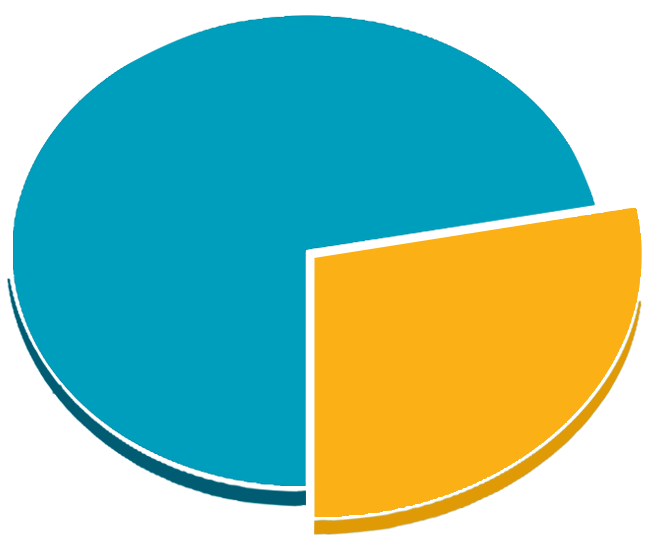
I

28%
SAVED (CISR)

*less interest

Interest Cost Comparison
(10 years)
A specialist Reverse Mortgage broker is best placed to help you get the right loan structure. The Home EquiSaver™ method is exclusive to Seniors First. 

Aside from paying the interest charge each month so tha the debt doesn't grow, Home EquiSaver™ is the best way for borrowers to:

  • Generate big savings on reverse mortgage interest costs 
  • Mitigate the compounding interest effect

USE A BROKER - GET THE RIGHT LOAN STRUCTURE

Enquire with Seniors First to discover your personalised Compound Interest Savings Ratio (CISR) Find out how much the right loan structure can your reduce potential interest cost, with our Home EquiSaver™ method. It’s 100% exclusive to Seniors First.
Impact on Your Estate Value

Because the Reverse Mortgage loan balance typically grows, your estate (what you leave to beneficiaries) may be reduced. For families, this can mean less inheritance.

However, protections exist:

  • No Negative Equity Guarantee – you can never owe more than the value of your home.
  • Any remaining equity after the loan is repaid still passes to your estate.

EXPERT TIP:

You can limit any negative impact on the estate value by paying the monthly interest to stop the loan balance growing. Some lenders also have a ‘protected equity feature’ which allows you to effectively quarantine a portion of the home equity for beneficiaries.
Loan Repayment Triggers

A Reverse Mortgage does not require repayments while you live in your home, but it must be repaid when certain events occur;

You sell your home.

You move permanently into aged care (some lenders);

You pass away (the loan is repaid from your estate, usually via sale of the property).

If a surviving spouse is listed as a co-borrower, they can continue living in the home until they also leave or pass away.
Will a Reverse Mortgage Affect My Age Pension?

GOOD NEWS: in the vast majority of cases Reverse Mortgage loans don't affect Age Pension entitlements. However it is possible under some circumstances,  depending on how the funds are used. Here are two use cases that are more likely to cause problems:

  • Loan funds deposited into savings or investments. Any money from the loan invested counts toward the Assets Test and may reduce your pension.
  • Gifting or loaning money to family. Loans or cash gifts are also counted as an assessable asset and can reduce entitlements, depending on the amount

Every case is different, so it’s always best to check with Centrelink’s Financial Information Service (FIS) before loan approval.

DID YOU KNOW:

The family home (principal place of residence only) is an exempt asset for the Age Pension test. So any Reverse Mortgage loan funds used on repairs or renovation will not impact entitlements.

Protections Under Australian Law

Reverse mortgages are the most highly regulated credit product in Australia.
Reverse Mortgage loans provided through specialist brokers, using recognised lenders, are very safe.

No Negative Equity Guarantee

this is a protection enshrined in law that you can never owe more than your home’s market value. All Reverse Mortgage lenders are required by law to provide a guarantee that should the debt grow to such level over time that it exceeds the value of the security property realised at the sale, then neither the borrower nor the beneficiaries of the estate, can be pursued for this shortfall after the sale has been concluded (as long as the borrower is not in default of the loan contract).

Put simply, if the sale of the security property is not enough to cover the debt, the lender bears the loss.In addition, the lender cannot force the borrower from the property if they think that the debt may have grown to a level where a shortfall may occur. 

Lifetime occupancy

You and your spouse have the right to live in your home for life, as long as you meet the loan conditions.

Mandatory legal advice

Lenders generally require you to seek independent legal and/or financial advice before signing. This provides an extra fail-safe check to ensure that you have understood

DID YOU KNOW:

Reverse Mortgage borrowers actually get a higher level of protection by going through a mortgage broker for their loan (as opposed to going direct to a lender). This is because brokers must abide by Best Interest Duty (BID) regulation, introduced in 2021. Lenders themselves do not have to meet this higher standard of customer care.

Risks & Benefits to Consider

Risks

  • Interest accumulation – loan balance can grow over time due to compounding.
  • Reduced inheritance – less equity may be left for children or beneficiaries.
  • Pension impacts – could reduce or eliminate Age Pension (in rare cases)
  • Future flexibility – borrowing heavily now may limit aged care or downsizing options later.

Benefits

  • Stay in your home - avoid or delay downsizing. Enjoy your current home and community as long as you want
  • Access tax-free cash - the funds are your home equity, they are not taxable
  • Flexible drawdown options - lump sum, income plan, cash reserve)
  • Protected by Australian law (No Negative Equity Guarantee)

Rated 4.9 stars on

“Sincere thanks to Andrew and Seniors First .. the loan has been life changing.”

Deborah Collett
Ian B. profile picture
Ian B.
2 days ago
At age 86 I was surprised to find that the bank I relied on for eighty years no longer provided reverse mortgages. Although very wary of the web I searched and found Seniors First which appeared well respected. My journey through the application process and the complications presented by an existing Government HEAS loan has been guided every step of the way to completion by their R. M. Specialist Cheryl Maclean. Thank you Cheryl and Seniors First – 100%.
Ramsay S. profile picture
Ramsay S.
6 days ago
Professional, caring, and very pleasant indeed! I don’t think there are many people out there who work with such dedication, and this is my second reverse mortgage signed successfully with Palka.
Mario B. profile picture
Mario B.
7 days ago
from the time we started to the time everything was done,Cheryl Maclean has been so helpful to us she has been there for us anytime we needed her.She is a huge credit to the company and it has been a pleasure knowing her .
Dina B. profile picture
Dina B.
1 week ago
Our experience with Cheryl has been nothing but amazing. She has helped along this process with much thought and dedication, she has been so patient and supportive throughout the whole experience. We definitely recommend Cheryl. Even when things were getting a bit complicated for us she was always patient. So many phone calls that we made to her she never made us feel like we were a nuisance. A very high praise to her. I’m sure as she went home at night she will feel she’s doing a great days work, for us and anyone else she’s helping. Thank you so much Cheryl for your help at this time of this experience we went through together. We are very grateful that you have been there for us. A very special thanks from Mario and Dina.
Peter W. profile picture
Peter W.
1 week ago
Thanks Angela Giokaris at Seniors First. Your help and guidance made it much easier to successfully apply for a Reverse Mortgage Loan.
Patricia A. profile picture
Patricia A.
1 week ago
Thank you for all your help... Very good too deal with
Richard H. profile picture
Richard H.
2 weeks ago
Angela Giokaris was our Reverse Mortgage Consultant at Seniors First to assist my wife and I to obtain a Reverse Mortgage. Angela's service was exceptional. She provided comprehensive information in a very user-friendly format and was always available to answer questions and provide clarifications. Angela secured an excellent interest rate following a competitive tender of available providers of Reverse Mortgages. My wife and I are very happy with the outcome and recommend Seniors First, and particularly Angela Giokaris, to other people interested in this product. Richard Hughes
Mark W. profile picture
Mark W.
2 weeks ago
Palka Kumar from Seniors First was excellent at guiding me through my Reverse Mortgage process.
Lorette S. profile picture
Lorette S.
2 weeks ago
I cannot speak highly enough of my experience with Cheryl Maclean her patience and guidance from my tentative inquiries to a result I am more than happy with. There was never a question I had that Cheryl couldn't answer confidently which in turn helped me make I believe the right decisions going forward. Thank you Cheryl
Sue H. profile picture
Sue H.
2 weeks ago
Cheryl has been an absolute godsend since day one. Nothing was too difficult. Always there to answer any questions or to give advice through this whole journey. I would recommend Cheryl to anyone contemplating a reverse mortgage Many thanks Sue
Jenni A. profile picture
Jenni A.
3 weeks ago
Our consultant Cheryl Maclean was at all times very professional. She answered all our questions and took us through the process smoothly and we felt very confident. We highly recommend her services.
Dorothy M. profile picture
Dorothy M.
3 weeks ago
I can not speak more highly about the way I was looked after and by Senior first / Reverse mortgage Broker I would and will recommend them to anyone else who needs help . Your's Faithfully Dorothy Mattsson .Thank you once again for their help.
Kathleen H. profile picture
Kathleen H.
3 weeks ago
My husband and I had a wonderful experience with Seniors First for our reverse mortgage especially the great help with our stock broker Cheryl Maclean from Seniors First she could not do enough for us in helping us get the best reverse mortgage loan for us in Inviva and making sure we understood the whole process Much appreciated Cheryl thank you 😊
lorraine G. profile picture
lorraine G.
1 month ago
.My first phone call to Seniors First was the wisest move in gaining financial security and confidence in my senior years. Due to the expertise and sound advice of my broker, Adam Oakley, the process was fast and efficient. His excellent communication skills and knowledge make me wish I had acted sooner. He was so patient and supportive throughout the process, especially when I was navigating the digital technology of my application. Thank you Adam
sandra T. profile picture
sandra T.
2 months ago
My reverse mortgage has just been settled and I am very grateful to my broker Richard Chapman for all his help and advice. Richard guided me through the process providing all information in a timely manner and was always available to clarify any questions which arose. His professional approach together with his warm and engaging manner made working with Richard a positive experience from start to finish. My heartfelt thanks to Seniors First and Richard for their valuable service.
Denise C. profile picture
Denise C.
3 months ago
My experience with my broker, Angela Giokaris, was excellent; she kept me fully informed about the process (providing clear instructions and a numbered checklist of the timeline) and the expected duration of the entire process, which in my case was 6 weeks. There was an issue with my own mortgagee which threatened to delay the settlement but in the end it was completed in time to suit my own needs. Throughout this relationship, Angela was always available and encouraging. We communicated and worked well together so I would recommend Angela to anyone seeking to engage Seniors First to provide a Reverse Mortgage.
Eric B. profile picture
Eric B.
3 months ago
I recently had dealings with Adam Oakley from Seniors First & cannot recommend him highly enough. From start to finish he was a total professional. All my enquiries were promptly answered & he made the process very smooth & uncomplicated 5 stars all the way!
Judy H. profile picture
Judy H.
3 months ago
We have had an excellent experience with Seniors First. Cheryl McLean helped us from our first phone call through to finalization. She explained the process in detail, she was efficient and friendly, and always answered our queries quickly. Highly recommend Cheryl
roland L. profile picture
roland L.
4 months ago
I must say that five stars does not seem enough to value the service we received from Palka Kumar of Seniors First. What a painless process she made of securing a reverse mortgage for us. We had been a little worried about the details involved in the process, but Palka took all the stress out of it. She was quick to respond to queries and anxious concerns and was always available. What is more she was so personable and friendly that we felt we had known her for ages. We could not possibly have achieved the positive result we have attained without her knowledgeable and insightful assistance. In short she was just marvellous and we highly recommend her expertise and her enthusiastic service from Seniors First. Roland and Shirley Lindenmayer Tamborine Mountain, Queensland.
Ann R. profile picture
Ann R.
4 months ago
I had been considering a reverse mortgage for some time and had read information from various companies about how it worked. After about five months, I decided to explore it more seriously and attended an online presentation by Seniors First, which clearly explained the process and who it might suit. I chose Seniors First because they focus on everyday seniors, and I felt more comfortable reaching out to them. I am very glad I made contact and was introduced to Angela. From our first phone call, she explained the ins and outs of reverse mortgages in a clear and reassuring way. She made sure I felt comfortable with everything we discussed before moving on to the next steps. Once I confirmed that I wanted to proceed, Angela arranged for all the information to be emailed to me and then followed up to make sure I understood everything. At times, the process felt complicated and stressful, and I called her several times to check that everything was correct. Her friendly manner, patience, and ability to answer questions clearly made the experience much easier and helped ensure all the paperwork was ready for processing. Angela was professional, knowledgeable, and extremely helpful. I particularly appreciated the breakdown she provided of the different banks’ interest rates and turnaround times. Once I decided which lender to go with, she shared examples of how easy they were to work with—and she was absolutely right. An Inviva representative also contacted me to explain how the reverse mortgage worked and to ensure that I fully understood everything before moving forward. After that call, settlement was scheduled for two days later. Although one party was not ready and this could have delayed the process by a week or more, Angela worked closely with the solicitors and helped make sure the loan still settled within the original two-day timeframe. The loan did settle, and I now know I made the right decision. I feel as though I can breathe again, knowing I have funds available if anything happens in the future. Thank you, Angela. Speaking with you felt like speaking with an old friend, and I truly appreciated your support.
Robert K. profile picture
Robert K.
5 months ago
Seema was extremely helpful and explain the process with us every step of the way. Anyone thinking of a Reverse Mortgage to use Seema from Seniors First would find it advantageous to do.

Frequently asked questions

Can I lose my home with a Reverse Mortgage?

No. As long as you follow the loan terms (paying rates, insuring, maintaining the property), you can remain in your home for life.

What happens when I die or move into aged care?

The home is sold, the loan and interest are repaid, and remaining funds go to you or your estate.

Is a Reverse Mortgage safe in Australia?

Yes. All lenders must comply with the National Consumer Credit Protection Act (NCCP), including the No Negative Equity Guarantee.

What can I use the money for?

Anything – common uses include paying off debt, covering healthcare or aged care, renovating for accessibility, or supplementing income.

How much are the set up costs for a Reverse Mortgage?

Allow about $1,500 – $2,500 in total to establish your Reverse Mortgage loan. This amount includes the main costs such as the lender application fee, government charges, legal advice fees, and broker fees. This is only an estimate; you could pay more depending on the circumstances. If you are low on cash, you can usually elect to pay these Reverse Mortgage costs from the loan proceeds.

Key takeaway

A Reverse Mortgage can be a lifeline for Australians over 55 who are “asset-rich but cash-poor.” It provides flexible access to the wealth in your home while you continue living there.

But it’s not without risks: compounding interest, potential Age Pension pension impacts, and reduced inheritance are all important factors. That’s why it’s crucial to get help from a specialist Reverse Mortgage broker before making a decision.

>